News · Italy
Italy introduces an exit tax: 26% on unsold assets when leaving from 2027
Updated: November 2026·8 min read·Expert reviewed
Terms and costs verified: November 2026
Contents
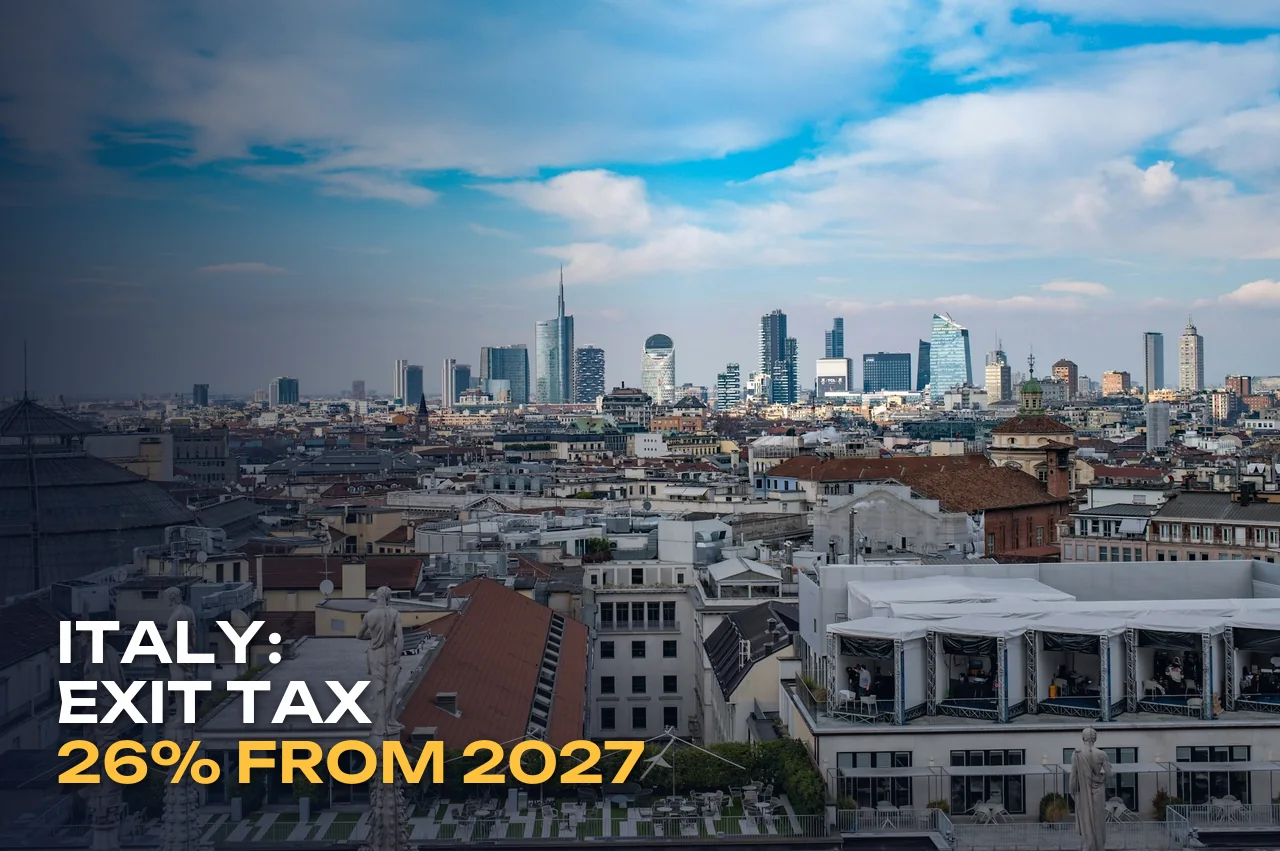
Italy proposes to tax gains a person has not yet realised at the moment they leave the country. Article 17 of the 2027 draft Budget Bill, which the government submitted to parliament at the end of October, introduces an exit tax for individuals: 26% on the growth in value of investments built up while living in Italy. It targets those who were tax resident for at least 6 of the last 10 years and hold assets of EUR 800,000 or more.
In brief
- Article 17 of the 2027 draft Budget Bill extends exit tax to individuals. Today it applies only to businesses.
- Conditions: Italian tax residence for at least 6 of the last 10 years and assets within scope of EUR 800,000 or more.
- Unrealised gains are taxed: the difference between market value and acquisition cost, even if nothing has been sold.
- The tax applies where residence is lost from 1 January 2027. Moving to an EU country allows deferral if 50% is paid at once and a guarantee is given.
- This is a bill. Parliament may change the text before the budget is adopted at the end of the year, so treat every figure as provisional.
What Article 17 proposes
Until now Italy applied a simple rule: when an individual stops being a tax resident, the move itself does not trigger tax. Exit tax existed only for companies, under Article 166 of the Consolidated Income Tax Act (TUIR). The 2027 draft budget changes this and extends the principle to private individuals.
The point of an exit tax is to let a country keep the right to tax gains that grew while the person lived there. On departure the assets are treated as if sold at market value, even though the owner keeps them and receives no sale proceeds. Tax is charged on the difference between market value and tax cost. The term is explained in our glossary.
The conditions in the draft are cumulative; the tax does not hit everyone who leaves:
| Condition | What the draft proposes |
|---|---|
| Residence period | Italian tax resident for at least 6 of the last 10 tax periods |
| Assets | total value of assets and rights within scope of at least EUR 800,000 |
| Trigger | a move after which Italy loses the right to tax income from those assets |
| Start | loss of residence from 1 January 2027 |
| Rate | 26% for financial assets, at the ordinary capital gains rate |
The EUR 800,000 threshold is the value of the assets in scope, not the amount of gain and not the person's total wealth. It is not a tax-free allowance: if the assets are worth EUR 900,000, the whole gain accrued on them is taxed, not just the part above the threshold.
What this means for you. If you have lived in Italy for more than five years and hold securities or a company stake worth EUR 800,000 or more, leaving from 2027 may cost you 26% of the accrued gain. Work this out before you move, not after.
Italy's budget law is adopted by 31 December, and during November and December both chambers usually table hundreds of amendments. The exit tax provision could leave parliament in a different form: with another threshold, another start date or a separate rule for flat-tax payers. So every figure in this report reflects the draft text, not an enacted law.
Who is affected: residence, not passport
The tax is tied to tax residence, not citizenship. Italians and foreigners alike can fall within it if the conditions are met. This matters for entrepreneurs, founders and investors who moved to Italy for several years and hold securities or business stakes.
There is a subtlety with dates. The draft values assets on the last day of the tax period before the year in which residence is lost. And loss of residence in Italy is determined by law and the relevant tax treaty, not by the date of physical departure. Someone who moved away in the second half of 2026 may, under Italian rules, remain resident for the whole of 2026 and lose residence only in 2027. The exit tax would then catch them even though they left before the start date. More on counting days and the centre of interests in our article on the 183-day rule.
Dmitry NagyInternational Tax Consultant, BRIDGES
Living in Italy and thinking of moving? We will calculate the exit tax before you decide
We will check your years of residence and your assets and show how the amount changes with different departure dates.
What it could cost: an example
Take an investor holding a securities portfolio. Market value EUR 2,000,000, tax cost of acquisition EUR 1,200,000. He moves to another EU country and asks for deferral:
| Item | Amount |
|---|---|
| Market value of the portfolio | EUR 2,000,000 |
| Tax cost of acquisition | EUR 1,200,000 |
| Unrealised gain | EUR 800,000 |
| Tax at 26% | EUR 208,000 |
| Due at once when moving to an EU country with deferral | EUR 104,000 plus a guarantee |
The tax arises without a sale. The owner keeps the securities but must find money for the tax elsewhere. For people whose wealth sits in a private company stake or illiquid assets, this becomes a liquidity problem: a stake often cannot be sold quickly at a good price.
The 26% rate is Italy's ordinary capital gains rate on financial assets. The draft does not set a single rate on all property: treatment depends on the type of asset. Italy keeps the right to tax real estate located in Italy after the owner leaves, and the exit tax covers only assets for which Italy loses that right. So the main impact falls on securities, funds and company stakes.
Three situations: who is hit hardest
- A founder moved to Milan in 2019 with a stake in his own start-up. It was worth almost nothing then and is valued at EUR 3,000,000 now. He has been resident for more than 6 years, the threshold is met, and almost the whole value is unrealised gain. Leaving from 2027 under this draft means tax of about EUR 780,000 without selling the stake.
- An investor arrived in 2023 and holds a portfolio of EUR 1,500,000. By 2027 she has 4-5 years of residence out of 10. If she leaves before reaching six years, the residence test is not met and the exit tax does not apply. For her the key question is the departure date.
- A family has lived in Italy since 2020 on the flat tax and holds foreign funds. Six of ten years are met and the threshold is passed. The draft does not say directly how the tax applies to their foreign assets. That is the main open question for such families.
These examples show that the exit tax changes the logic of planning. Previously, years in Italy affected annual taxes and the right to apply for citizenship. Now the sixth year of residence also becomes the point after which leaving with a large portfolio costs money. Count that clock from your first year in the country, not when the decision to leave has already been made.
Deferral: half up front and a guarantee
The draft allows payment to be deferred where a person moves to an EU country or a state that exchanges tax information with Italy. The terms are tough: 50% of the tax is paid at once and a guarantee is provided. Deferral lasts up to five tax periods for moves within the EU and up to ten for other qualifying countries.
The draft also foresees cases where the deferred tax may lapse if the assets are not sold during the deferral period. But deferral is not an exemption. The first 50% and the guarantee are already a serious sum and a burden on capital. The final rules on payment, guarantees and refunds will only be clear from the enacted text. It is also worth checking how your destination country treats the exit tax: if it taxes the same gain again on a later sale without a credit, you face double taxation.
What this means for the new residents' flat tax
For years Italy has attracted wealthy people with a flat tax on foreign income under Article 24-bis TUIR. A new resident pays a fixed sum instead of ordinary tax on foreign income, for up to 15 years. The amount has risen: EUR 100,000 a year at launch, then EUR 200,000, and EUR 300,000 for those entering the regime from 1 January 2026.
The draft does not say directly how the exit tax will interact with this regime. The 6-out-of-10-years test could formally cover people who paid the flat tax for several years. How gains on foreign assets would then be calculated is not yet clear. It is too early to conclude that the exit tax will hit every flat-tax payer, but equally unsafe to assume it will not.
The main change for anyone choosing a country: Italy must now be assessed not only on tax on arrival and during residence, but also on the cost of leaving. We made the same point in our review of tax regimes for new residents. For financially independent people considering Italian elective residence or the investor visa, this is a new item in the calculation.
Italy is not the first in Europe
Other EU countries also have an individual exit tax, for example France under Article 167 bis of the General Tax Code. Yet as early as 2004, in the de Lasteyrie du Saillant case, the EU Court of Justice found France's former exit tax to be a restriction on freedom of establishment, partly because of its deferral conditions. That ruling does not mean the Italian rule necessarily breaches EU law, but it gives grounds to challenge harsh deferral terms for moves within the Union.
When comparing countries, look at the full picture: tax on arrival, annual taxes, tax on departure and inheritance. Malta tax residence with its new 2027 rules, Cyprus tax residence and the UAE work differently, and none automatically beats the others. On inheritance tax with a second citizenship, see our separate article.
What to do now
Count your years
How many of the last ten tax periods you were Italian resident. The sixth year is the point after which the tax may arise.
Value the assets in scope
Securities, funds, company stakes. Compare market value with acquisition cost and check the EUR 800,000 threshold.
Check the date residence ends
What decides is not the departure date but the year Italy stops treating you as resident. Law and the tax treaty determine that.
Wait for the final text
The budget is adopted by year end. Until then do not sell assets in a hurry: conditions and exemptions may still change.
We are following the budget through parliament and will update this report when the text of Article 17 is adopted. If you already live in Italy or plan to, see our overview of Italian taxes and the elective residence guide, and we will run the numbers for your situation in an online consultation.
Share this article
Frequently asked
Questions people ask before deciding
01Who will the Italian exit tax affect?
Under the draft, individuals who were Italian tax residents for at least 6 of the last 10 years and hold assets within scope of EUR 800,000 or more.
02What is taxed?
Unrealised gains: the difference between the market value of the assets and their tax cost, even if they have not been sold.
03When does the tax apply?
The draft applies it where Italian residence is lost from 1 January 2027. It is a bill and the text may still change.
04Can payment be deferred?
Yes, when moving to an EU country or a state that exchanges tax information: 50% of the tax at once plus a guarantee, with deferral of up to 5 or up to 10 tax periods.
05Does the tax affect flat-tax payers?
The draft does not settle this directly. The 6-out-of-10-years test could formally include them; how foreign assets would be treated is not yet clear.
About the author
Related materials
What to read next
 ArticleItaly's flat tax: fixed tax on foreign income for new residents
 AnalysisTax for new residents in 2026: Italy, Greece, Portugal, Turkey and the UAE
 ArticleItalian citizenship by birth in 2026: children, jus soli and reality
News+12 stories on 9 November
Related news
 Italy · 28 OctItaly issued 47% more residence permits in 2025, with a 15-year high in family permits
 Italy · 27 OctItaly and Spain end border checks: ordinary Schengen rules apply again from 24 October
 Italy · 25 OctItaly debates a citizenship bill: B1 certificate for all applicants and new grounds for revocation
Personal programme selection is conducted by Anna Kovalevskaya, Head of Legal, BRIDGES.
Choosing a country to live and pay tax in? We will compare arrival, living and leaving
We will calculate taxes in Italy, Malta, Cyprus and the UAE over 10 years, including the cost of departure.