Updated
SRV-LS-IC
Legal structures
An international companya link in your structure
A company in a structure is not an end in itself but an instrument: it holds assets, settles with foreign counterparties or separates operating risks from family capital. We choose the jurisdiction to fit the company’s role and check that a bank will accept the construct.
- First the company’s role in the structure, then the choice of jurisdiction
- We check it will pass with the banks before registration, not after
- We do not register companies where an account cannot afterwards be opened
01 / The service
What role a company plays in a structure
One and the same form — an “international company” — solves entirely different problems. The role governs the choice of country, the requirements as to presence and which bank will agree to serve it.
A holding company
It holds shareholdings in other companies and collects dividends. Double taxation treaties and the rules on withholding tax matter here — so not every jurisdiction will do.
A holding-of-assets company
It owns property, a portfolio or intellectual property. The task is convenient ownership and clear succession, not turnover.
A trading company
It carries out real settlements with counterparties. Here the bank becomes decisive: without a working account and a clear supply chain the company is useless.
An intermediate link
A company between the asset and a trust or foundation: it separates the risks and allows the ownership to change without re-registering the asset itself.
02 / Situations
When a company solves the problem
The situations where we genuinely recommend this instrument.
Settlements with foreign counterparties
You need a company a bank will accept and that counterparties are ready to work with without extra checks.
Owning property abroad
Holding it through a company makes succession and sale simpler: the owner of the shares changes, not the owner of the property in the register.
Separating risks
The operating business is separated from the assets: a claim against the operating company does not touch the family’s property.
A partnership with several participants
The shares, the voting rights and the exit procedure are fixed in the corporate documents, not in verbal understandings.
A link under a trust or a foundation
The top level of a structure rarely owns assets directly — usually a company stands between them.
Entering a new market
Working in the Gulf, Europe or Asia often requires a local or regional legal entity.
03 / Honest limits
When a company is not needed
More often than people think — and we say so directly.
Just to have one
A company with no task means annual costs for administration, reporting and explanations to banks. If there is no role, do not register it.
To avoid tax
The CFC rules and the exchange of information make such constructs pointless. A company changes the tax picture lawfully only together with real substance.
To conceal the owner
Nominee directors and shareholders do not hide the beneficial owner from the bank or the registers, and they raise questions immediately.
In a blacklisted jurisdiction
Registering where no account can be opened and where counterparties will refuse to work is money spent for nothing. We talk clients out of such options.
If the task can be solved without a company, we will say so — it is cheaper for you and more honest.
04 / Scope of work
What the work covers
From settling the role to a company with an account and clear reporting.
Settling the role
What the company does in the structure, who owns it, who runs it, where the money comes from and where it goes.
Choosing the jurisdiction
We compare two or three options on tax, the requirements as to presence, the running cost and whether banks will take it.
Registration
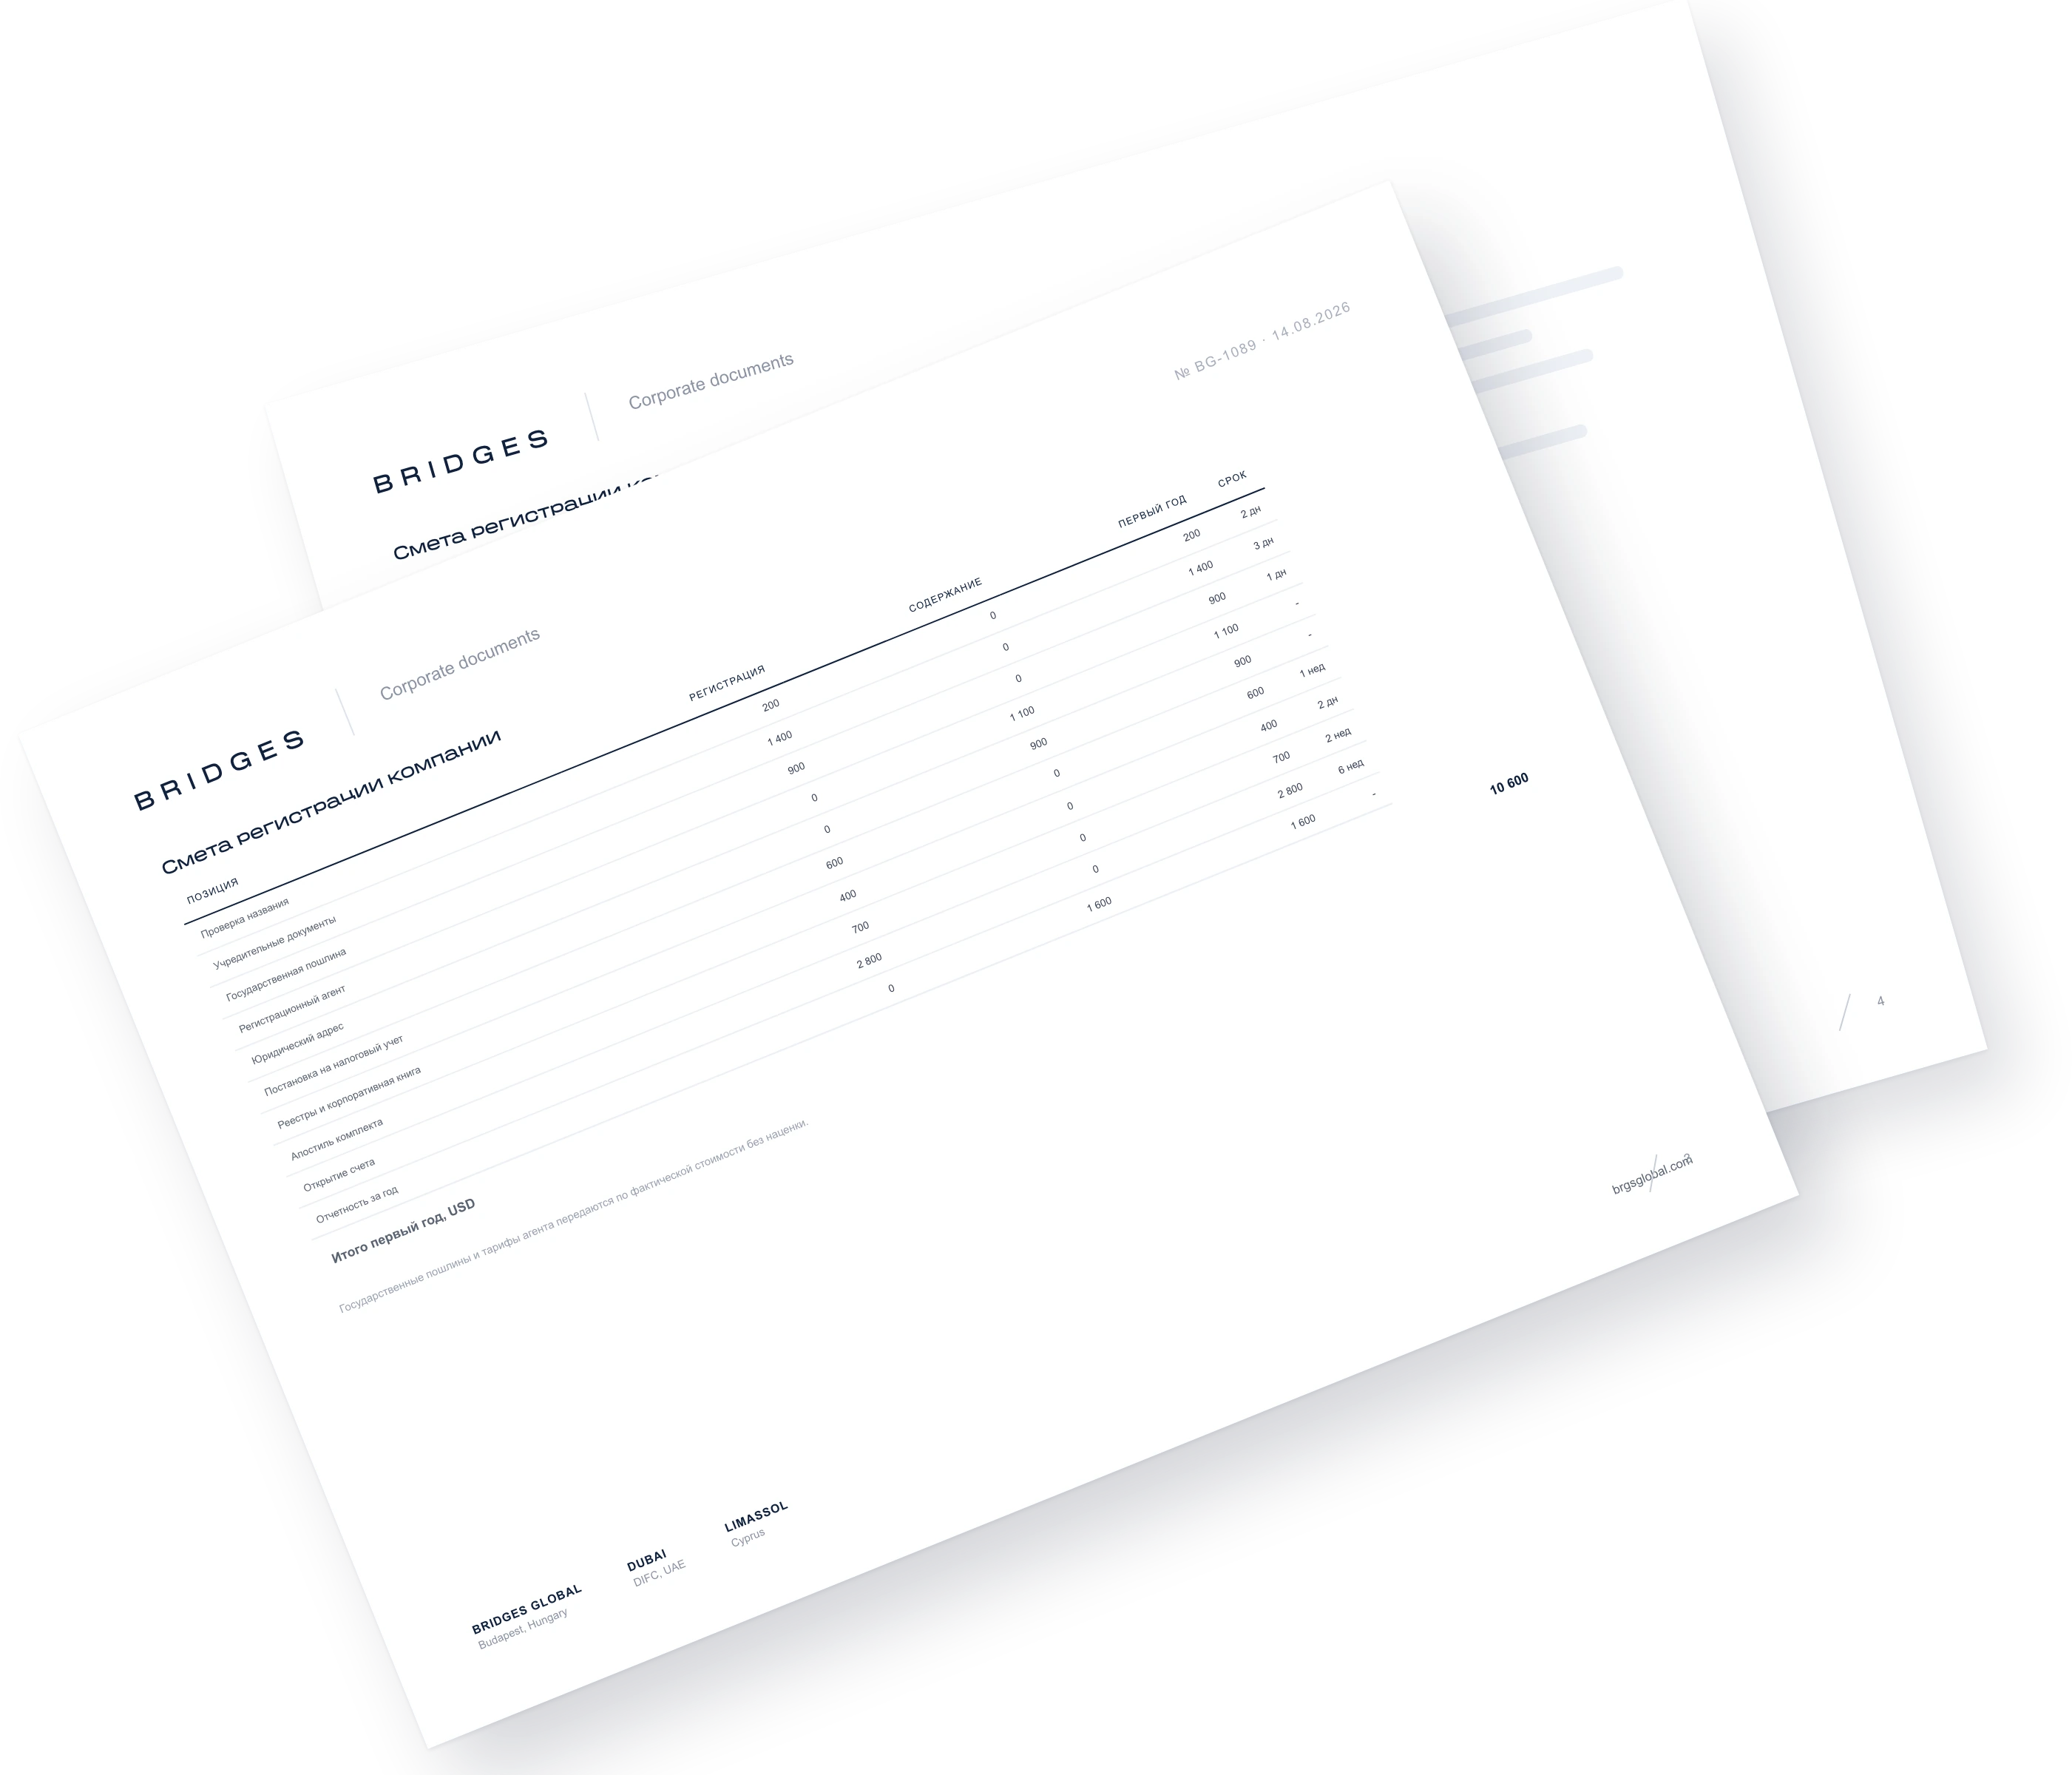
The constitutional documents, the paid-up capital, appointing the organs, registration in the register and registration for tax.
Opening the account
We choose a bank to fit the company’s profile and prepare the file. The account is a compulsory part of the result, not a separate hope.
Corporate arrangements
A shareholders’ agreement, the procedure for decisions, the rights on exit and on disagreement — where there is more than one owner.
Annual support
The reporting, the renewal, changes in the organs, economic substance where it is required.
The registration procedure by country is set out in detail in the section on company registration — here what we answer for is the company’s role in the structure.
05 / Cost
What the cost depends on
It is calculated by the jurisdiction and the requirements as to presence, not by turnover.
The jurisdiction
The spread is wide: the Caribbean and Middle Eastern jurisdictions cost less to register, the European ones more, but they pass more easily with banks and counterparties.
The requirements as to presence
An office, a local director, staff, evidence of economic substance — where these are compulsory the running cost is markedly higher.
The banking stage
Opening an account is quoted separately: the volume of the file depends on the bank and on the company’s line of business.
The number of participants
Several owners means a shareholders’ agreement and a compliance check on each of them.
We show the annual running costs before registration: an unexpected renewal invoice is the worst way to learn about them.
06 / How it works
How we work
From the company’s role to a working account.
Going through the task
What role the company plays, who owns and runs it, what flows are expected.
1–2 days
Choosing the jurisdiction
A comparison of the options on tax, presence, cost and banks — with a recommendation.
3–5 days
Registration
The documents, the capital, the organs, the register, registration for tax.
1–4 weeks
The bank account
Choosing the bank, the file, the interview, opening it and setting up access.
3–8 weeks
Support
The reporting, the renewals and the changes as the company works.
The timing depends on the jurisdiction and the bank: opening an account almost always takes longer than registering.
07 / Preparation
What we will need from you
Compliance checks the company and the people behind it alike.
The participants’ documents
Passports, proof of address, details of the tax residency of every owner and director.
A description of the business
What the company will do, whom it will work with, what turnover is expected and where the payments will go.
The origin of the funds
Evidence of the source of the company’s capital — required by the registrar and by the bank alike.
The existing structure
Which companies and assets there already are — the new company has to fit into them rather than contradict them.
The full breakdown of the requirements for the file is on the page about evidencing the source of funds.
08 / Team
Who runs the work
The registration and the banking stage are run by different specialists but in one project.
 Robert HaasCorporate LawyerChoosing the jurisdiction, the registration and the corporate documents
 Yan NovakWealth Structuring AdvisorThe tax side and the requirements as to presence
 Klara RihterHead of Compliance and Due DiligenceThe file and opening the bank account
 Daniel KovachSenior International Law AttorneyRepatriation and archive documents
10 / Questions
Answers to common questions
The answer depends on the role. For settlements with European counterparties you need a jurisdiction their banks will accept. For holding assets the running cost and ease of succession matter more. We compare two or three options on your own task rather than giving a universal list.
In some jurisdictions, yes, especially where the structure is transparent and the file is prepared in advance. Many banks, above all in Europe and the Gulf, require a meeting with the beneficial owner in person. We say so before the start, so that the trip does not come as a surprise.
A requirement in a number of jurisdictions to evidence that the company really carries on business in the country of registration: an office, staff, expenditure, decisions taken locally. Where it applies, a shell company does not pass — and that has to go into the budget.
Yes, if you are a tax resident of a country where such a duty exists. For Russia that means the notification of participation in a foreign organisation and reporting under the CFC rules. We build that into the plan from the outset rather than remembering it a year later.
In part: it separates corporate risks from personal property. But it does not protect against claims made against you personally as the owner of the shares — for that you need the top level of a structure, a trust or a foundation.
From a few days in the Emirates and the Caribbean to three or four weeks in Europe. But registration is not the finish: another three to eight weeks pass before there is a working account, and the planning should run from that date.
In some jurisdictions it is compulsory by law; in others it is needed in practice for the bank and for the company’s tax residency. It is a noticeable line of expenditure, and we show it in the budget before registration rather than after.
Nominee services exist and are lawful as a management tool, but the ultimate beneficial owner is disclosed to the bank and, where required, to the register. Hiding yourself that way is impossible, and an attempt to do so is read by compliance instantly.
From a token sum in the Caribbean and Middle Eastern jurisdictions to tens of thousands in Europe, and part of the capital sometimes has to be paid in before registration. That money stays the company’s funds; it is not a fee for registering.
The obligations remain: the fees, the reporting, the renewal. A dormant company is either kept deliberately or wound up properly. Simply stopping payment is the worst option: it ends in being struck off the register and a frozen account.
INITIAL ASSESSMENT
Tell us what outcome your family needs
We will design a solution for your case, choose the country and the right status, and take the whole process through to the result.
