An account with AED, USD, EUR balances and in-bank conversion. The base of the client’s settlement infrastructure in the jurisdiction.
Updated 19.08.2026
FAB · UAE
FAB private banking in the UAEfor owners of capital
Support in establishing a relationship with First Abu Dhabi Bank’s private banking arm. For clients with verifiable capital: custody, investment solutions and multi-currency infrastructure at the UAE’s largest bank.
- PRIVATE BANKING
- MULTICURRENCY
- SWIFT
- INVESTMENTS
- UAEJurisdiction
- AED · USD · EURMain currencies
- For non-residentsApplications considered
- Per bank termsOpening format
Overview
Key terms
FAB is the UAE’s largest bank. Its private banking arm serves wealthier clients: multi-currency accounts, investment portfolios, premium cards. Entry thresholds and terms are agreed with the bank individually; every case passes an extended source-of-wealth review.
- Account type
- Private banking
- Client
- Including non-residents — per bank requirements
- Currencies
- AED · USD · EUR
- Bank card
- Yes, per the selected bank product
- SWIFT
- Yes
- SEPA
- No: EUR payments run via SWIFT
- Opening
- In-person visit / per current bank terms
- Timeline
- Individual: private banking reviews each case separately
- Bank fees
- Set by the bank; shown before the work starts
- BRIDGES GLOBAL service
- Individual, after the preliminary check
Products
What you get
An international payment card linked to the account — physical and digital formats per the bank’s line.
Online banking and a mobile app: payments, conversion, statements and bank communication remotely.
File preparation, filing coordination and responses to bank requests — before the decision and after opening.
Bank card
Debit card
- Payment network
- Visa or Mastercard — per bank product
- Currencies
- AED · USD · EUR
- Format
- Physical and digital card
- Delivery
- At a bank branch at opening or later
- Mobile wallets
- Per current bank terms
- Maintenance
- Per bank tariffs; shown before the project
Card issuance and maintenance terms are set by the bank. Before the project we confirm the current tariffs of the selected product.
Non-residents
For clients without UAE residency
FAB private banking also works with non-residents — given verifiable capital and a clear structure of its origin. Citizenship, country of residence and source of wealth are assessed together; a resident visa broadens the available line.
- Entry thresholds follow bank requirements and are discussed individually
- Verifiable source of wealth is the key to the review
- A UAE resident visa broadens the product line
Availability
Availability by citizenship
Select citizenship:
Statuses reflect review practice as of the verification date and are not a promise on the bank’s behalf. The bank makes the final decision on each specific application.
Requirements
What the applicant needs
The arm serves clients whose capital meets the bank’s thresholds and is documented.
The history of the capital is the main review subject. We build the evidence chain before the bank introduction.
Custody, investments, settlement infrastructure or all three — the task is defined before filing.
The banker introduction happens in person. We arrange the meeting and prepare the client.
Preparation
Documents for the bank
The exact list depends on citizenship, residency and source of funds: after the pre-check we send a personal list with samples.
Source of funds
Pick your main source — we show the documents the bank typically requests.
Documents usually required
- Employment contract or employer letter
- Salary account statements
- Tax returns where applicable
Pricing
BRIDGES GLOBAL support packages
Account and core support until the bank’s decision
Adds card issuance and digital banking set-up
Adds support for bank compliance requests for 6 months after opening
Included
- Preliminary check
- Personal document list
- Application and banking file preparation
- Visit booking and coordination
- Bank communication support
- Responses to additional bank requests
Not included
- The bank’s decision to open the account
- Bank fees and tariffs
- Minimum balance and deposits
- Third-party costs: translations, apostilles, travel
Process
How the account opening works
- 01Pre-check
We assess citizenship, residency, source of funds and account purpose — and say honestly whether the application has a prospect.
- 02Payment and project creation
Once the fit is confirmed we invoice the service. The project gets a number and a personal coordinator.
- 03Document collection
We send a personal list, verify each document and request anything missing in advance.
- 04Banking file
We build the file in the logic of compliance questions: source of funds, account purpose, expected operations.
- 05Filing and visit
We coordinate the branch visit in Dubai or Abu Dhabi, prepare the client for the bank’s questions and support the filing.
- 06Compliance review
The bank reviews the application. We answer additional FAB requests and keep the client informed.
- 07Bank decision
The decision belongs to the bank. If declined, we analyse the reason and propose the next step — keeping the prepared file.
- 08Account and card
We help activate the account, the card and digital banking. On the extended package we stay available for bank requests.
Compliance
Compliance and source of funds
The bank assesses not the size of the capital but its clarity: where the funds come from, what the client does, what operations are planned. We prepare the file in this logic before filing, so most compliance questions close in advance rather than in correspondence after filing.
The final decision on opening the account, issuing the card and providing banking products belongs to the bank. BRIDGES GLOBAL provides consulting and support services and does not guarantee a positive bank decision. Payment is made for BRIDGES GLOBAL services in preparing and supporting the project.
Questions
Account opening questions
Thresholds are set by the bank and discussed individually — they depend on the service mix and booking jurisdiction. We give reference points at a consultation after the task is assessed.
By the level of tasks: private banking means custody and management of capital, investment mandates and structuring — not just a card with perks. The source-of-wealth review is accordingly deeper.
For a standard personal account — yes, together with an Emirates ID. Some banks offer non-resident savings accounts with higher balance requirements — we check this scenario at the pre-check. If there is no visa, the visa-plus-account setup is handled as one project.
Most banks set average monthly balance requirements below which a fee applies. Thresholds depend on the bank and the service tier — we confirm them before the project.
A reference point is several days to four weeks: it depends on the product, the applicant’s status and the FAB review.
Payment covers BRIDGES GLOBAL’s preparation and support work, not the bank’s decision. We start with a free pre-check and do not take on applications without a realistic prospect. Termination terms are fixed in the agreement before payment.
Team
Who runs banking projects
 Dmitry NagyInternational Tax ConsultantBanking solution shortlist and the preliminary client check
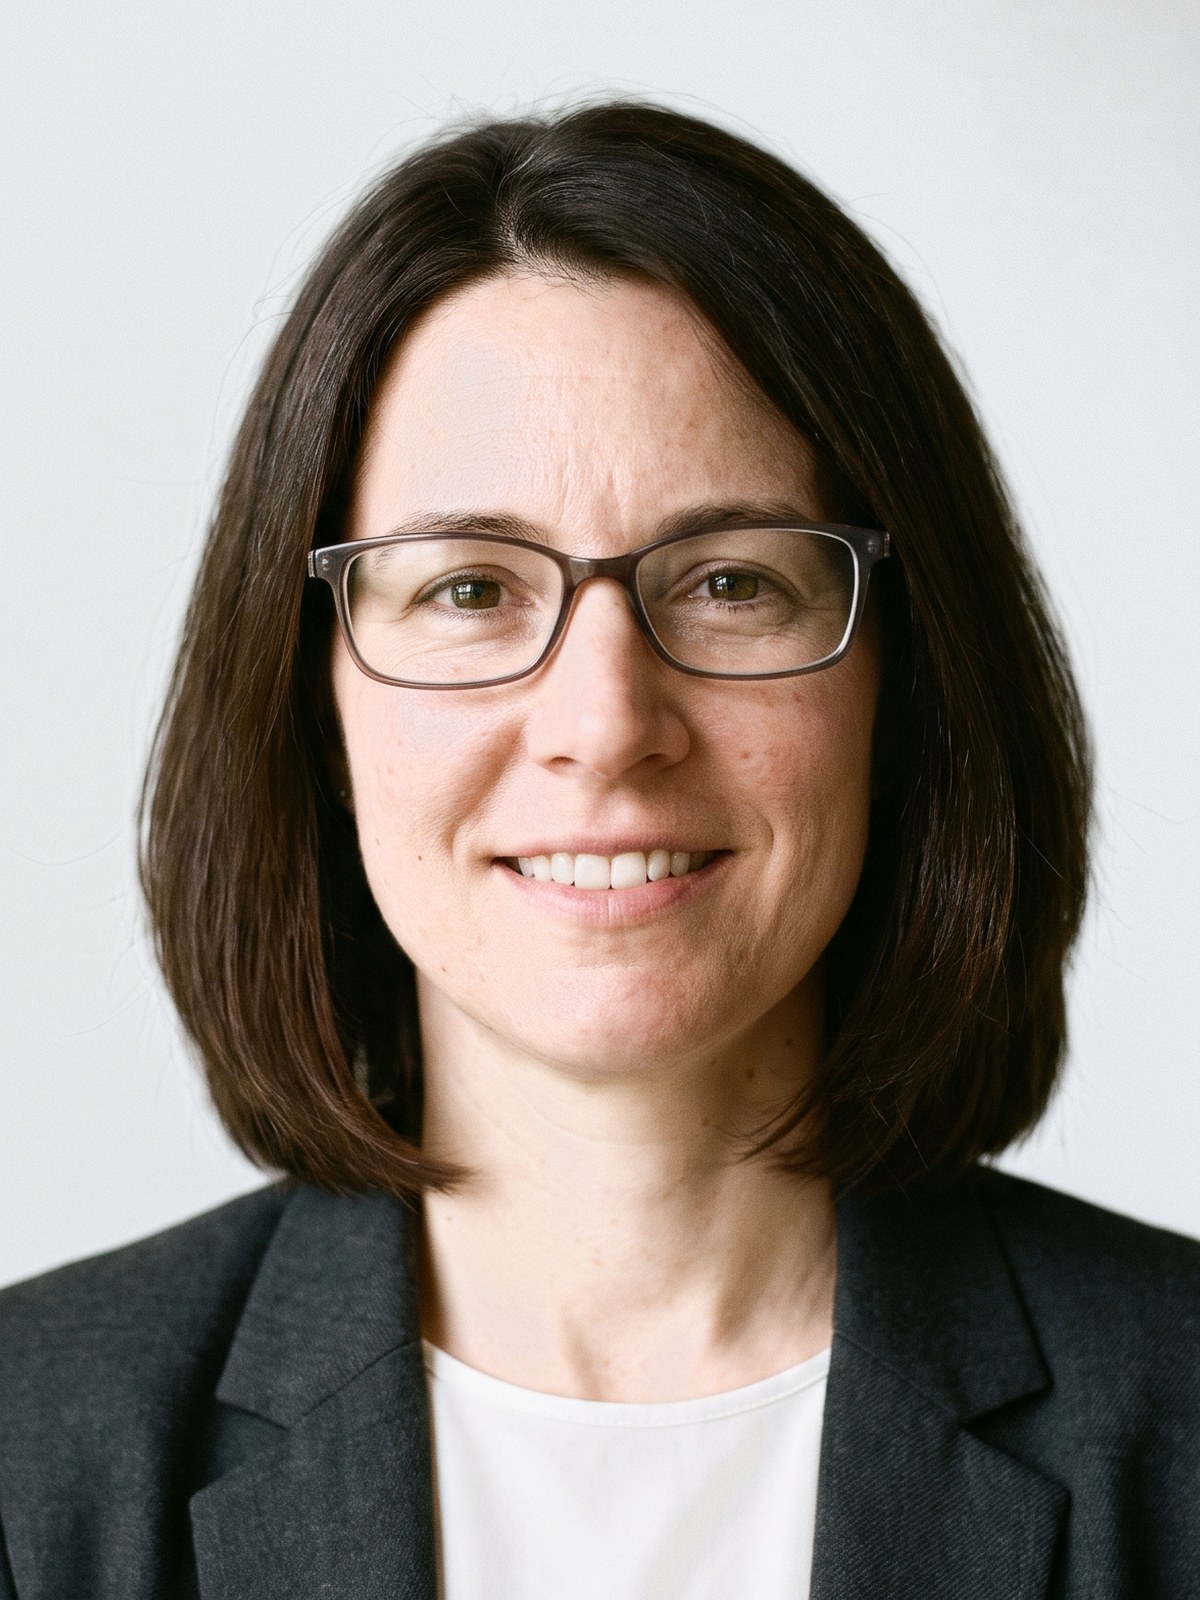 Klara RihterHead of Compliance and Due DiligenceThe banking file and source of funds
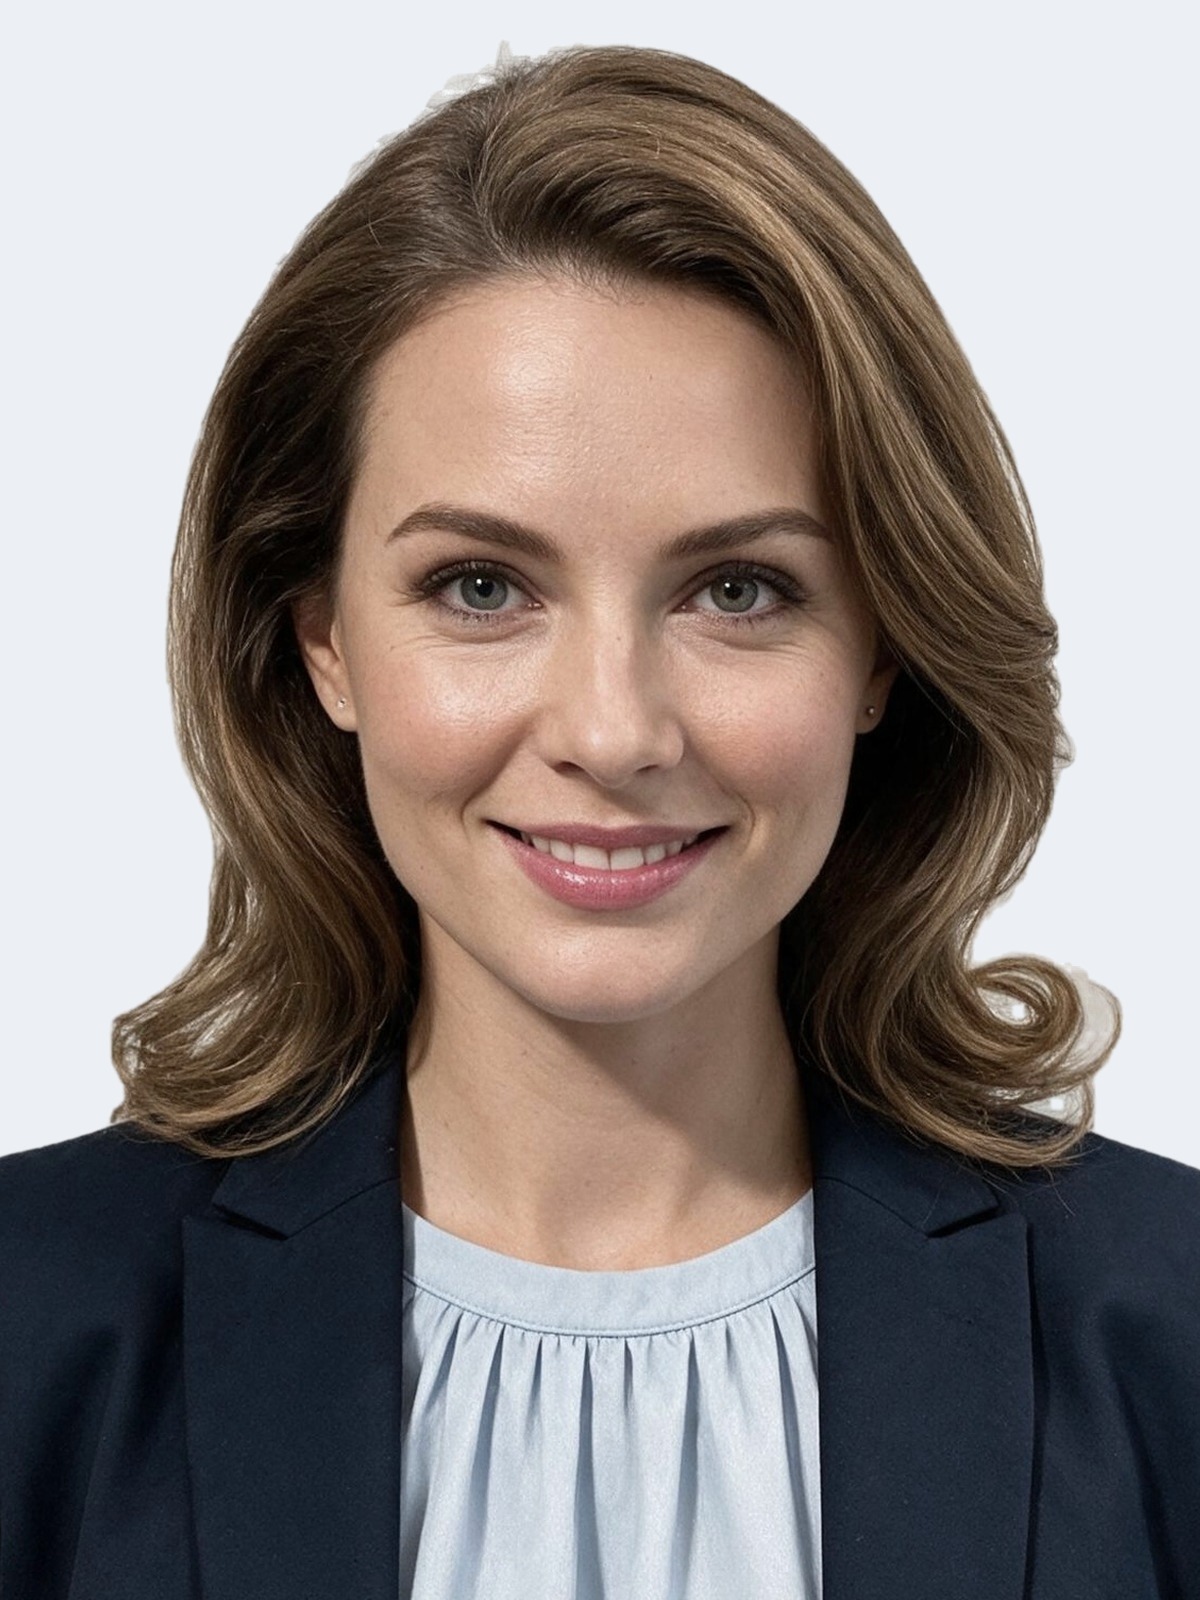 Elena TitovaClient Relationship ManagerProject coordination and client liaison
- 20+ yearsof international practice
- 8,000+families obtained status with BRIDGES GLOBAL
- 40+countries and jurisdictions in work
Availability
Another solution may fit you better
 UBS
 LGT
IndividualFAB · Private banking