Updated 13.08.2026
 Legal structures · Trusts
A Cook Islands trust the benchmarkin asset protection
The Cook Islands were the first in the world to write a law specifically for asset protection — in 1984. Case law under it has been building for forty years, and that is precisely why the Cook Islands trust is treated as the industry benchmark: a creditor has to prove the case again, before the Cook Islands court, under local rules.
- Forty years of case law — a predictable outcome rather than a theory
- We say plainly what the trust will not protect you from — before you sign
- We prepare the source-of-funds file for the trustee and the bank
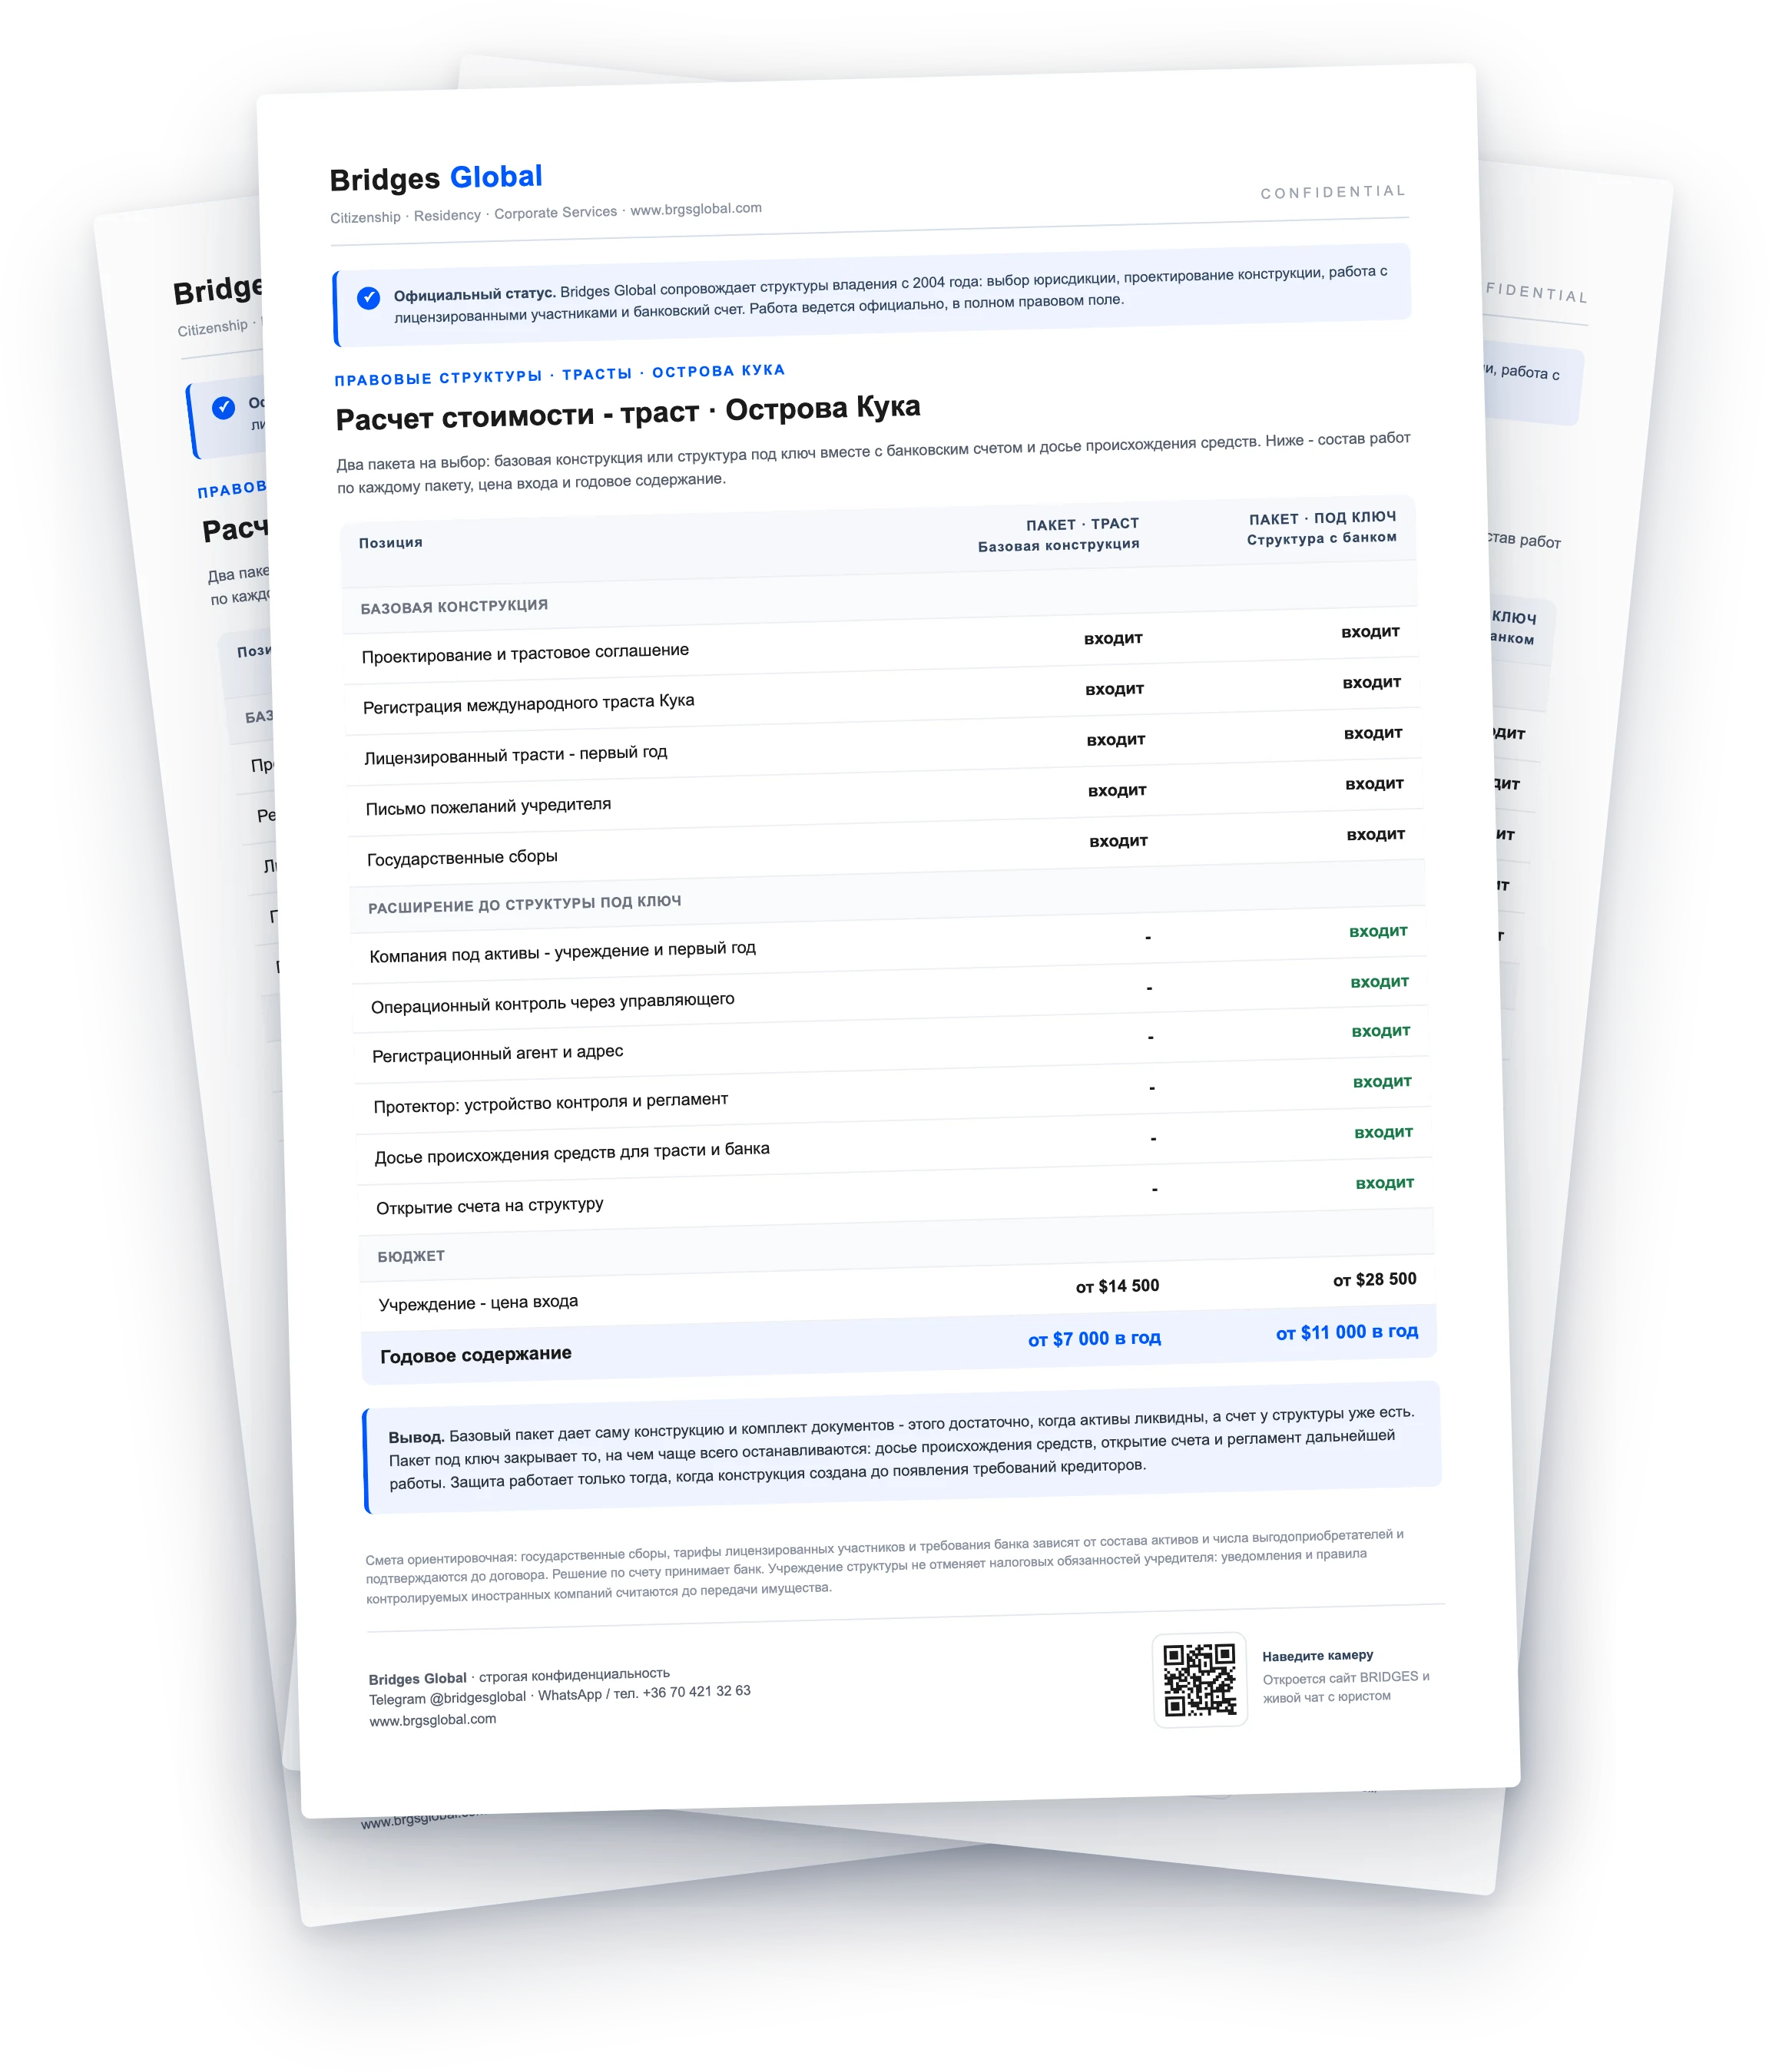
The guide figures depend on the composition of the assets, the number of beneficiaries and the bank’s requirements. The exact quotation for the set-up and the annual upkeep is fixed before the agreement.
Applicability
Is Cook Islands the right structure for your task
01 Main purpose
02 Assets
03 Beneficiaries
04 Bank account needed
The selector does not give a legal opinion: applicability is confirmed after the analysis of assets, family and tax residence.
The structure
What a Cook Islands trust is
It is an international trust under the International Trusts Act 1984 — a law written not for tax but precisely to protect capital against future claims. You transfer the assets to a licensed trustee, who owns them in the interests of your family under the rules you have written into the deed.
The Cook Islands were the first jurisdiction to codify asset protection. Forty years have produced a body of case law, including high-profile matters involving US regulators: it shows where the protection works and where it does not. Predictability here is worth more than any promise.
A foreign judgment against a Cook Islands trust is not enforced as such. The creditor has to litigate in the islands, under local law, with local counsel and to a heightened standard of proof — proving an intent to defraud.
A transfer of assets can be challenged only within a limited period running from the transfer. It runs regardless of when the creditor learned of the trust — which is why the structure is created in advance, not when a dispute is already on the horizon.
You are not left without levers: the protector may replace the trustee and approve distributions and major transactions. The rules are fixed in the deed and in the letter of wishes.
Fit
Applying the structure: when it fits and when it does not
A plain filter: this is an expensive structure for substantial capital over a long horizon.
- Capital from $1-2m: portfolios, accounts, shareholdings, real estate held through a company
- A profession with a high exposure to claims: a doctor, a developer, a business owner
- Succession by rules instead of wills and disputes between heirs
- Assets in several countries and the need for one set of rules
- A planning horizon measured in generations rather than a couple of years
- A dispute has already begun or a claim is expected: a late transfer can be set aside
- The aim is to avoid tax: a trust is declared, and we build only transparent structures
- The budget does not carry the upkeep: Cook Islands trustee fees are higher than Caribbean ones
- You need daily personal control over every asset — then a trust is not your instrument
Roles
The legal structure and the parties
The construction holds together on the distribution of roles — each with its own rights and its own limits.
Transfers the assets and sets the rules. After the transfer they do not own them personally — that is both the protection and the price of the decision.
A licensed Cook Islands trust company supervised by the local regulator. The legal owner of the assets, bound by the deed and by the law.
Your lever of control: replacing the trustee, vetoing distributions, approving major decisions.
Those for whom the trust is created: the family, the children, you yourself. The names are not published in public registers.
Protection
The legal limits of using the structure
We name the strengths together with the limits: the decision is taken on facts.
A judgment of a Russian, EU or US court against a Cook Islands trust does not operate directly: the proceedings start again in the islands.
The claimant has to prove that the transfer was made specifically to their detriment — under the local standard that is a difficult and expensive task.
Assets transferred before the marriage or before the dispute arose do not form part of the divisible property or of the estate.
The death or incapacity of the settlor does not stop the structure: the trustee goes on performing the written rules.
The limits we state plainly: a trust does not protect against claims that arose before the assets were transferred. It does not cancel the tax obligations of the settlor and the beneficiaries and does not make assets invisible — the exchange of information and the duty to declare both operate. Criminal proceedings, sanctions regimes and maintenance lie beyond what any structure can do. Anyone who promises otherwise is misleading you.
Prices
The options for the structure and the cost
The «from» prices are for a standard structure with a confirmed source of funds. The exact quotation is fixed by the agreement: there are no charges beyond the quotation.
from $14,500
Annual upkeep: upkeep thereafter from $7,000 a year
Protecting liquid assets: accounts and securities portfolios
Included
- Design and the trust deed
- Registration of the Cook Islands international trust
- A licensed trustee — the first year
- The settlor’s letter of wishes
- Government fees
from $19,500
Annual upkeep: upkeep thereafter from $9,000 a year
Business shareholdings and real estate: the assets are held by an underlying company
Included
- Everything in the «Trust» package
- A company to hold the assets — formation and the first year
- Operational control through the manager
- The registered agent and the address
from $28,500
Annual upkeep: upkeep thereafter from $11,000 a year
Family capital for generations: the complete circuit, bank included
Included
- Everything in the «Trust + company» package
- The protector: the control arrangement and its terms of reference
- The source-of-funds file for the trustee and the bank
- Opening the account for the structure
- A plan for distributions and succession
The package does not include the bank’s own charges, legal work in the countries of the assets when real estate and shareholdings are transferred, or a professional protector if you want one.
What drives the quote
The factors that affect the cost of the project
The packages cover the standard tasks. Here is what moves the budget — and it is counted before the agreement, not after.
Accounts and portfolios are simple. Real estate and shareholdings in companies require lawyers in the countries where they are held.
Every country of assets adds a check and the formalities of the transfer.
Capital from several sources over a long period takes longer to document than a single sale of a business.
Banks differ in what they require: for some the basic pack is enough, others need an extended one.
In the quotation we separate our own fee, the trustee’s fees and the government charges. The total is fixed by the agreement.
Cost of ownership
The cost of the structure over three years
A structure costs money not only when it is created: administration, reporting and bank compliance recur every year.
- Creating the structure and the documents
- Registration and government fees
- Opening the structure’s bank account
- The first year of administration
- Administration of the structure
- Reporting and mandatory notifications
- Bank compliance and the KYC refresh
- Support of distributions to beneficiaries
- Administration of the structure
- Reporting and mandatory notifications
- Bank compliance and the KYC refresh
- A review of the structure as circumstances change
What each year contains depends on the jurisdiction, the assets and the bank’s requirements. We prepare the three-year calculation together with the set-up quotation — before the agreement.
Tax
Taxation, reporting and disclosure
A Cook Islands trust is exempt from local tax on income earned outside the islands. Your own obligations are determined by your country of tax residence — we design the structure with that in mind, not against it.
A trust is a foreign structure without the formation of a legal entity: its establishment is declared, and where there is control the CFC rules apply. We build it so that the reporting is workable.
The Cook Islands take part in the automatic exchange. Data on the structure’s accounts goes to the beneficiaries’ country of tax residence — that is the norm, not a failure.
If a move is planned, the tax picture changes. We work through the structure and the residence together rather than separately.
The trustee keeps records and reports to the islands’ regulator. That is the price of the jurisdiction’s reliability.
We do not build arrangements to conceal income and we do not work with funds whose origin is not evidenced by documents.
Banking
The banking infrastructure of the structure
A trust without an account is paper. The bank checks both the structure and the origin of the capital, so we prepare the file in parallel with the establishment.
Switzerland, Liechtenstein, Singapore, the UAE — depending on the profile of the assets, the residence and the amount. We choose the bank for your case, not «whichever will take it».
Who the settlor and the beneficiaries are, where the capital came from, what the structure is for, who takes the decisions. The logic has to read from the documents without spoken explanations.
The sale of a business, dividends, salary, an inheritance — each source is evidenced by a chain of documents. That is the core of the approval.
Opening an account for a trust structure takes longer than for a company: we build that time into the plan from day one.
A refusal by a bank is not the end: we work out the reason and go to the next one with the file corrected. No one guarantees approval, and neither do we.
Documents
Documents and information for the establishment
We assemble the pack once — the same pack goes to the trustee and to the bank.
- 01Personal documents Passports and proof of address: the settlor, the protector, the beneficiaries.
- 02The source of the capital Sale agreements, bank statements, dividend resolutions, tax returns.
- 03The list of assets What is going into the trust: accounts, portfolios, real estate, shareholdings — with the title documents.
- 04Tax residence The countries and the taxpayer numbers of every party: the notifications and the reporting depend on them.
- 05The rules for distributions Who receives funds, when and on what conditions — these rules go into the settlor’s letter of wishes.
- 06Current obligations Claims, debts, guarantees and disputes: they determine whether the protection works at all.
No documents are needed at the first consultation — we work through the task in words.
Comparison
Compare Cook Islands with other structures
| Cook Islands | |
|---|---|
| Setup | from $14,500 |
| Annual | upkeep thereafter from $7,000 a year |
| Timing | 3-5 weeks |
| Typical use | Capital from $1-2m: portfolios, accounts, shareholdings, real estate held through a company |
Select up to two jurisdictions above. A detailed legal comparison is prepared for the specific task.
Process
The stages of establishing the structure
From the review of the task to a finished structure with an account.
What is being protected, against what, who the beneficiaries are, whether there are current disputes. At this step we say plainly whether a trust is needed at all.
1-2 daysThe roles, the rules for distributions, the protector’s powers, exactly what goes into the trust and how.
3-5 daysIdentity documents and source-of-funds evidence for the trustee and the future bank.
1-2 weeksThe trust deed, the appointment of the trustee, registration, the letter of wishes.
2-3 weeksMoving the assets into the trust with correct formalities in the countries where they are held.
Opening the structure’s account and setting the working rules: who does what, and in what order, from here on.
Comparison
The Cook Islands against the alternatives
The main parameters side by side, so that the choice is an informed one.
| Cook Islands | Nevis | BVI | Cyprus | |
|---|---|---|---|---|
| The year of the protection law | 1984 | 1994 | 1993 (VISTA 2003) | 1992 |
| Case law | Forty years, extensive | Substantial | A corporate focus | EU case law |
| Foreign judgments | Not enforced | Not enforced | Partially recognised | Recognised in the EU |
| Establishment | 3-5 weeks | 2-4 weeks | 2-4 weeks | 2-3 weeks |
| Cost from | $14,500 | $12,500 | $13,500 | $9,500 |
The comparison is as at the date the page was updated; whether it applies to your case is confirmed once the profile has been reviewed.
FAQ
Questions and answers
A longer body of case law, stricter supervision of trustees and higher fees charged by the licensed companies. You are paying for predictability: there are forty years of judgments on Cook Islands trusts to rely on when designing the structure.
Legally — yes, and that is the essence of the protection: the assets are no longer your personal property. In practice control is preserved through the protector and the letter of wishes. A trust in which the settlor manages everything personally is treated by the courts as a sham.
Yes. Establishing a foreign structure is not prohibited. The obligations are to declare it and to apply the CFC rules where there is control. We build the structure so that the reporting is workable, and we do not work with capital whose origin cannot be evidenced.
No. Sanctions restrictions apply to the person regardless of how the ownership is arranged. We check the sanctions profile before the work begins and say plainly if the structure does not solve the task.
That is the working scenario the structure is created in advance for: a claim that arose after the assets were transferred attacks the trust from the weaker position. The reverse — a transfer made after the claim arose — can be set aside.
Decades: the Cook Islands law allows a long duration, enough to pass capital down the generations under rules written in advance.
Calculation
Structure and budget: Cook Islands
Describe the assets, the family and the task. We will come back with the applicable structure, the setup budget and the annual upkeep.
A structure does not cancel existing creditor claims or the tax obligations of the settlor. Where the task cannot be solved lawfully, we say so before the engagement.