Updated
SRV-BA-PA
Bank accounts · For individuals
A personal account abroadto fit your profile
A personal account is not opened “at any bank” but at the one that works with your citizenship, your residency and your source of capital. We check in advance that the profile will pass, prepare the file and run the opening through to a working account with a card and access to the app.
- We check the profile will pass before filing
- We prepare the file and run the correspondence with compliance
- We stay with you to the first payment made
01 / The service
How a personal account is opened today
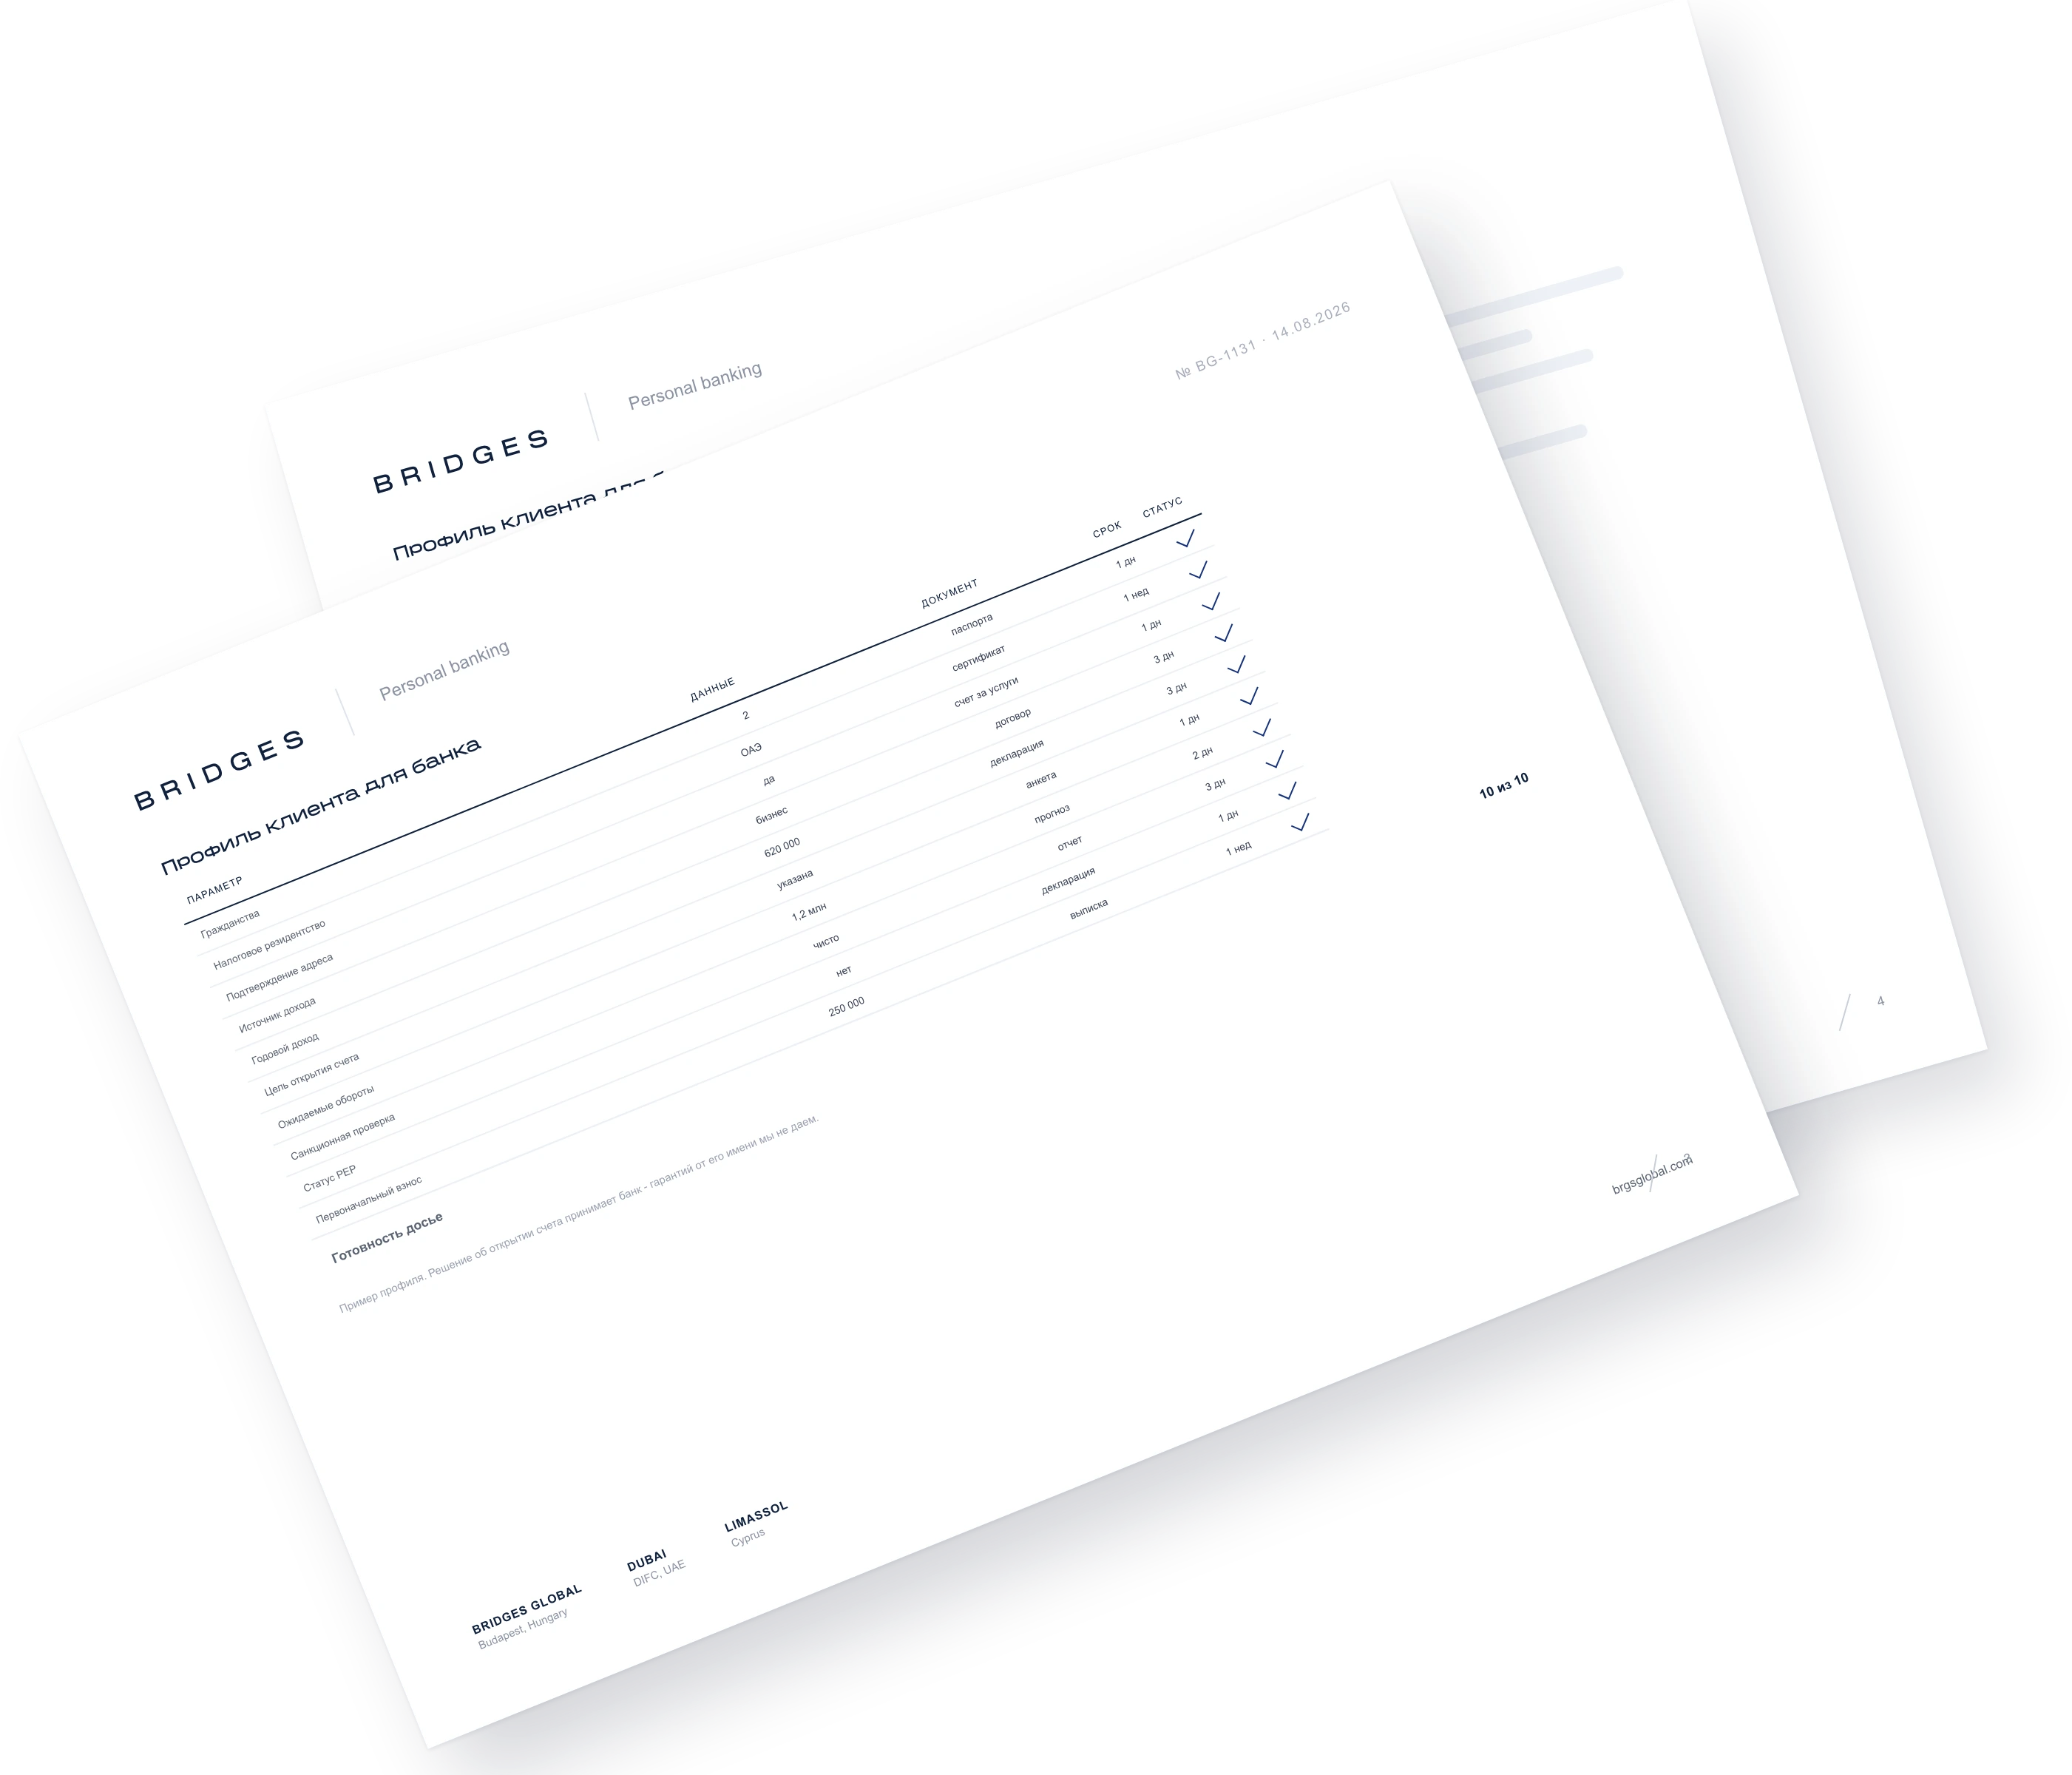
The days when an account was opened on a passport are over. Now the bank studies your tax anchor, the origin of your capital and the purpose of the relationship — and only then decides. So the work starts not with choosing a bank but with going through your profile.
The profile decides everything
Citizenship, tax residency, country of residence, source of capital and expected turnover — on these parameters some banks open an account in two weeks and others refuse at the door.
Residency widens the choice
A residence permit or a second citizenship enlarges the list of available banks, sometimes dramatically. If there is no status, we discuss honestly whether it is not wiser to obtain one first.
The purpose of the relationship
Holding capital, everyday spending, investments, settling property deals — different tasks lead to different institutions with different requirements.
A file is compulsory
Even for a personal account the bank asks for evidence of the origin of funds. Without it the application is not considered on its merits.
02 / Situations
When an account abroad is needed
The typical situations people come to us with.
Buying property abroad
The deal is settled through an account: without one the notary and the seller will not work, and the contract’s deadlines are burning.
Paying for a citizenship or residency programme
State contributions are accepted by transfer from the applicant’s account. The account is often opened before the documents are filed.
Living and spending in another country
Rent, the children’s schooling, medicine, everyday spending — a local account and a card are needed.
Holding and spreading capital
Spreading funds between jurisdictions and currencies so as not to hold everything in one place.
Investments
A brokerage or investment account to work with a portfolio of securities.
Receiving income from abroad
Dividends, rental income, proceeds from selling assets.
03 / Honest limits
When we will decline the task
Directly and before the work starts — so as not to waste your time.
The origin of the capital cannot be evidenced
With no documented source of funds no account will open anywhere. It is the first thing any bank checks and the check cannot be got round.
The aim is to hide the account from the tax authority
The automatic exchange of information works: details of the balances will go to your country of residency. We do not build concealment arrangements and we help you notify the authorities properly.
Sanctions restrictions
If the client is under restrictions, opening an account is impossible in most jurisdictions. What is needed there is a legal assessment of the situation, not a search through banks.
An account “in someone else’s name”
Registering it to a nominee to conceal the real owner is a direct breach for which everyone involved answers. We do not take such work on.
A refusal at this stage is more honest than months spent and a banking history spoiled.
04 / Catalogue
Where we open personal accounts
The direction is chosen for the task: to hold capital, to spend while travelling, to evidence funds for a residency. We name the particular bank at the review — for your citizenship, your residency and the origin of your capital.
- 2–6 weeksOpening
- From CHF 250,000The usual threshold
- A visitAs a rule required
The classic for holding capital: deposits, a portfolio, several currencies. The highest requirements as to the origin of funds.
- Holding capital
- Investments
- Several currencies
- 2–6 weeksOpening
- From CHF 300,000The usual threshold
- Often remotelyThe format
The same currency and reliability as Switzerland, with a more flexible onboarding. It works well paired with a structure.
- Holding capital
- An account for a structure
- 2–8 weeksOpening
- ResidencyMakes it much simpler
- AED, USD, EURCurrencies
An account for living and settling payments in the region. With a resident visa it opens noticeably more easily and faster.
- Living in the country
- Settlements
- Paired with residency
- 3–6 weeksOpening
- No thresholdEntry
- EURThe main currency
A European account with a clear procedure. It often goes together with buying property or permanent residence on the island.
- An account in the EU
- Property
- Evidencing funds
- 4–10 weeksOpening
- From SGD 200,000The usual threshold
- A visitAs a rule required
The Asian centre for holding capital: reliability, investment products, strict compliance.
- Holding capital
- Investments
- Asia
- 2–8 weeksOpening
- A connection with the countryThe condition
- GBP, EUR, USDCurrencies
An account for living, the children’s schooling and running a property. An evidenced connection with the country is required.
- Living in the country
- The children’s schooling
- Property
We do not publish the names of banks on the site: the choice follows the profile, and we are not entitled to promise a decision on a bank’s behalf.
05 / Scope of work
What we do
The full cycle: from going through the profile to a working account.
Going through the profile
Citizenship, residency, capital, aims. We assess which banks really work with such a set and which will refuse at the door.
Choosing the bank
A shortlist of institutions where the profile passes, with the honest pros and cons of each — the timing and the requirements as to presence included.
The file and the origin of funds
We assemble the set to the requirements of the bank chosen: the source of capital, evidence of status, a description of the business.
Filing and correspondence
We fill in the forms, file the application and answer compliance’s questions in your name. The client does not have to conduct that dialogue.
Support for the visit
If the bank requires you in person, we prepare you for the meeting: what will be asked, what to bring, how to answer. Where needed we arrange the trip.
Bringing the account to life
Access to the app, the card, the first payment — we take it to the point where the account can be used.
We prepare and we support. The account is opened in your name and only you give instructions on it — we do not take powers of attorney over funds.
06 / Cost
What the cost depends on
It is calculated by the type of bank, the complexity of the profile and the volume of preparation.
The jurisdiction and the type of institution
Swiss private banking and a payment institution in the UAE are different amounts of work, with different requirements and timelines.
The complexity of the profile
Citizenship, residency and connections with higher-risk countries affect the volume of checks and correspondence.
The state of the documents
A ready file on the origin of funds shortens the work; assembling one from nothing and restoring what is lost takes longer.
The number of accounts
Several accounts in different jurisdictions are quoted separately, but part of the preparation is reused.
The estimate is fixed before the work starts. If a bank refuses, choosing the next one and improving the file are covered by the support at no extra charge.
07 / How it works
How we work
From the first conversation to the first payment made.
Going through the profile
We discuss the citizenship, the residency, the source of capital and the purpose of the account. No documents are needed at this step.
1 day
Choosing the bank
We give a shortlist of institutions with an honest assessment of the chances and the timing at each.
2–3 days
Preparing the file
We assemble the set to the requirements of the bank chosen and clear the gaps and contradictions.
1–2 weeks
Filing the application
The forms, the documents and the covering explanations about the profile and the purpose of the relationship.
2–5 days
The consideration
Compliance studies the file and puts follow-up questions — we answer them.
2–6 weeks
Opening and starting up
The signing, access to the app, the card issued, the first payment.
The time for consideration is set by the bank: it depends on compliance’s workload and the complexity of the profile, and we do not influence it.
08 / Preparation
What we will need from you
The basic set is much the same at almost every bank.
A passport and proof of address
A passport, a second document, a utility bill or a bank statement showing the address of residence.
Evidence of status
A residence permit, a second citizenship, a certificate of tax residency — if you have them. That widens the list of available banks.
Documents on the origin of capital
Contracts, statements, tax returns, dividend resolutions, certificates of inheritance — the base of the file.
A description of the business
What you do and where the income comes from. The bank studies that alongside the documents, so the wording matters.
No documents are needed at the first consultation — we go through the profile in words.
09 / Team
Who runs the work
The profile is assessed by a lawyer, not by a sales manager.
 Klara RihterHead of Compliance and Due DiligenceAssessing the profile, the file and the correspondence with the bank
 Karim NaserHead of Istanbul OfficeGathering the documents and supporting the client to the opening
 Hanna BergerTrusts and Succession AdvisorThe tax side: residency, the exchange of information, the notifications
 Sergey EvdokimovManaging PartnerStrategy, capital, complex matters
11 / Questions
Answers to common questions
There is no such bank — there is the bank that suits your profile. For a business owner with UAE residency that is one institution; for someone with property in Europe, another. So we do not name a bank before going through the profile: promising a particular name blind would be misleading.
It depends on the bank. Some institutions open an account remotely, others require a visit for identification and signing. We say so before the choice is made and plan the trip so that several tasks are closed at once.
Yes, in a number of jurisdictions — but the list of banks is markedly narrower and the requirements higher. If residency or a second citizenship is planned in parallel, it is often wiser to open the account once you have the status: the choice is wider and the terms better.
Yes, if the country takes part in the automatic exchange — details of the balances and turnover will go to your country of tax residency. That is the norm, not a failure. We work with declared capital and help you meet the duty to notify the authorities that the account has been opened.
Go through the cause — the formal one and the actual one, which often differ — close the gap in the file and go to a bank that works with such a profile. Firing identical applications at ten banks only spoils the history.
No. We prepare the documents and run the correspondence with the bank. The account is opened in your name and only you give instructions on it. We do not take powers of attorney over funds as a matter of principle.
At some banks it is compulsory, especially in Switzerland and Liechtenstein. Many banks in the Gulf and Europe open accounts remotely with a complete file. We say whether a trip is needed before the work starts, so that it does not come as a surprise.
From nothing at digital institutions to hundreds of thousands at the private banks of Switzerland. The threshold is rarely decisive: what matters more is the client’s profile and how clear the origin of the funds is.
From two weeks to three months. Most of the time goes on compliance rather than on the paperwork. A file assembled in advance halves it — which is exactly why we start with it.
First get the balance and the statements, then work out the likely cause, and only then file at a new bank. Filing without that work most often leads to a second refusal for the same reason.
If you are a tax resident of a country where such a duty exists, yes. In Russia a notification that the account has been opened and a report on the movement of funds are filed. Having the account is lawful; what is punished is the silence.
INITIAL ASSESSMENT
Tell us what outcome your family needs
We will design a solution for your case, choose the country and the right status, and take the whole process through to the result.
