Residency · UAE
Secondary property in Dubai 2026: buying a ready home and how it differs from off-plan
Updated: June 2026·12 min read·Expert reviewed
Terms and costs verified: June 2026
Contents
Secondary property in Dubai means a ready home with a Title Deed already in place: you see the actual apartment and move in or rent it out from day one, rather than waiting three years for a building to go up from a render. In 2026, resale is on average 25-30% cheaper than new builds per square meter, but it requires payment in full or a mortgage, and the deal runs through the developer's NOC and re-registration at the Dubai Land Department with a 4% fee. We break down, step by step, how to buy a resale property in Dubai, how a ready home differs from off-plan, and where the resale market beats off-plan.
What secondary property in Dubai is and how it differs from off-plan
Secondary property in Dubai is a ready property that has already been built, handed over, and issued a Title Deed - the certificate of ownership held at the Dubai Land Department (DLD). Such a property already has an owner - either a developer selling the remaining units of a completed phase, or a private owner reselling their apartment or villa. Unlike an off-plan property at the foundation stage, here you are buying not a promise on paper but actual walls, a real view, and a specific floor that you can touch before the deal.
The key practical difference is simple: a resale property can be occupied or rented out from the first day after re-registration. An off-plan property is the purchase of a project under construction, with staged payments and a wait for handover that often stretches to 2-4 years. While construction is under way, the property generates no rental income and exists only as project documentation and an Oqood registration, not a full Title Deed.
- Resale (ready) - a ready home, the Title Deed already exists, move-in and rental straight away, paid in full or through a mortgage.
- New build (off-plan) - a property under construction, Oqood registration, an installment plan from the developer, income only after handover.
If you are only getting to know the market, start with the general overview in our guide to property in the UAE, and then return to the details of the resale market. Buying a ready home gives what off-plan lacks: predictability and an immediate return.
Ready property vs off-plan: the key differences point by point
The choice between resale and off-plan is not a question of 'which is better overall,' but of your objective. An investor who needs rental income from day one leans toward a ready home. Someone willing to wait for the sake of an installment plan and potential appreciation during construction is suited to off-plan. To make the comparison concrete, here is a table across the main criteria. The price figures are indicative, based on Dubai market data from early 2026, and depend on the district and the project.
| Criterion | Resale (ready) | New build (off-plan) |
|---|---|---|
| The property's condition | Built, can be inspected in person | Under construction, judged by render and plan |
| Certificate of ownership | The Title Deed is already issued | First Oqood, then the Title Deed after handover |
| Move-in and rental | Immediately after re-registration | Only after handover (in 2-4 years) |
| Price per sq m (indicative) | Lower, ~1,690 AED/sq ft | Higher, ~2,030 AED/sq ft |
| Payment | In full or with a mortgage | An installment plan from the developer |
| The developer's NOC | Mandatory on resale | Not required (first sale) |
| DLD fee 4% | At the moment of re-registration | On signing the contract (SPA) |
| Rental income | From day one | After construction is completed |
| Construction risk | None | Handover delays, project changes |
As you can see, resale wins on predictability and speed of return, while off-plan wins on the entry threshold and payment terms. Our detailed look at the off-plan side is kept in our article on buying off-plan new builds in Dubai. From here, we focus specifically on the ready market.
The advantages of buying ready property on the resale market
The strengths of a ready home are, above all, certainty. You are buying not a project but a specific physical asset, and that removes a whole layer of risks that are unavoidable when buying under-construction housing. Let's list the main advantages of resale in Dubai.
- You see the actual property. You can inspect the apartment in person and assess the finish quality, the real view from the window, noise, natural light, the state of the building, and the district's infrastructure. A render shows none of this.
- Income from day one. A ready home can be rented out immediately after re-registration. In 2026, it was precisely apartments with a sitting tenant that proved the most resilient in demand - the buyer earns a yield immediately, rather than after years of waiting.
- A lower entry price per square meter. The difference in average price per square meter between ready and under-construction housing in Dubai holds at 25-30% in favor of resale - ready homes are cheaper per meter.
- Genuine liquidity and the Title Deed in hand. A ready home with a completed certificate of ownership is easier to resell and to pledge against a mortgage - the bank sees a real asset to value.
- Room to negotiate. On the resale market, prices are negotiable. In certain segments in 2026, properties are selling 5-15% below the peak values of the start of the year - a private seller is willing to give ground, which almost never happens with a developer on the primary market.
For those who see the purchase as part of a relocation or residency strategy, a ready home is more convenient: it is immediately fit to live in. The overall logic of the purchase is covered in our guide to property in Dubai.
The drawbacks and risks of resale that you should know
A ready home is not a cure-all, and the resale market has its own weak spots. Let's go through the drawbacks so the decision is measured rather than emotional.
- A higher financial entry threshold. The main drawback: resale usually has to be paid for in full or financed with a mortgage. The convenient long installment plan from a developer, as on off-plan, is almost non-existent here. A large sum is needed up front.
- Less appreciation potential 'during construction.' The lion's share of off-plan appreciation happens during the construction period. By buying a ready home, you have already skipped that growth phase - subsequent movement depends on the market as a whole.
- Condition and wear. A property may need renovation or new appliances, or carry service-charge arrears. All of this must be checked before the deal, otherwise the costs fall on the new owner.
- Dependence on the seller. If the property carries a mortgage from the seller, it has to be paid off within the deal, which complicates and lengthens the process. A clean deal with no encumbrances is always faster.
- The NOC and service-charge debts. The developer will not issue the No Objection Certificate until the seller clears all maintenance debts. This is an extra step that does not exist on the primary market.
None of these drawbacks is critical if the deal is handled by a competent specialist and all checks are done in advance. But they cannot be ignored: it is precisely on unchecked debts and encumbrances that buyers most often lose time and money.
How to buy resale in Dubai: the step-by-step deal process
Buying a ready home on Dubai's resale market is a well-established and transparent procedure, carried out under the oversight of the Land Department (DLD) and the RERA regulator. Let's go through the deal step by step so it is clear what it consists of.
- Step 1. Choosing and inspecting the property. You pick an apartment or villa in a freehold zone (Marina, Downtown, Business Bay, JVC, Dubai Hills, etc.), inspect it in person, and check the property's condition and history.
- Step 2. The Form F agreement (MOU). The buyer and seller sign the DLD's standard contract - Form F, also known as the Memorandum of Understanding. It sets out the price, the deposit, the payment schedule, and the terms for completing the deal.
- Step 3. The 10% deposit. The buyer pays a deposit, usually 10% of the price, typically by a manager's cheque. The cheque is held by a RERA-accredited agency until the transfer of title is completed or the deal is lawfully cancelled.
- Step 4. Obtaining the NOC from the developer. The seller obtains a No Objection Certificate from the developer - confirmation that the property has no service-charge arrears. Without the NOC, re-registration is impossible.
- Step 5. Re-registration at the DLD. The parties meet at the office of an accredited DLD trustee, pay the balance of the price (usually by manager's cheque), the 4% DLD fee, and the administrative charges. The DLD issues a new Title Deed in the buyer's name.
On timing: a clean deal with no mortgage and no encumbrances on the seller's side takes roughly 3-6 weeks from signing Form F to the issue of the Title Deed. A mortgage adds time for bank approval. We cover the basic algorithm for buying an apartment in detail in our article on buying an apartment in Dubai.
The developer's NOC: what it is and why it's needed on resale
The No Objection Certificate (NOC) is perhaps the key difference between a resale deal and a primary-market purchase. The document is issued by the property's master developer, and without it the Land Department will not register the transfer of ownership. The point of the NOC is straightforward: the developer confirms that the seller has no arrears on service charges or other obligations to the community, and that it does not object to the deal.
What's important to know about the NOC when buying resale in Dubai:
- This is a mandatory step for any resale. When buying a ready home on the resale market, the NOC is always required - it is part of the transfer-of-title procedure.
- On the primary market the NOC is not needed. When you buy a property directly from the developer as a first sale (off-plan or a new ready unit from the developer), you do not arrange an NOC - there is simply no previous owner with debts.
- The cost is a developer's fee, not a DLD one. The NOC costs roughly 500-5,000 AED for standard housing, most often in the 1,000-3,000 AED range. It is a payment to the developer, not a government fee.
- The condition for issue is cleared debts. The developer will not issue the NOC until the seller clears all service charges. Debts on the property are therefore the seller's headache, one that must be settled before going to the trustee.
The practical takeaway: on the resale market, always allow time and a small budget for the NOC, and before signing Form F, check whether the property has any outstanding service payments. This will keep the deal from collapsing at the final step.
Re-registering the Title Deed at the DLD: the final step of the deal
The Title Deed is the certificate of ownership of property in Dubai, the equivalent of a title certificate. For a ready resale home, the Title Deed already exists in the seller's name, and the point of the deal is to re-register it to the buyer at the Dubai Land Department. That is the legal moment of transfer of title.
How the re-registration works:
- A meeting at the DLD trustee's office. The buyer and seller (or their representatives under a power of attorney) attend an accredited Registration Trustee centre - the DLD-authorized centres for registering deals.
- Payment of the balance and fees. The buyer hands over the balance of the price, usually by a bank cheque made out to the seller, and pays the DLD fee - 4% of the property value - plus the administrative charge for a ready home (roughly 580 AED) and the trustee-office services (roughly 4,000-4,200 AED).
- Issue of the new Title Deed. After registration, the DLD cancels the old document and issues a new Title Deed in the buyer's name. From that moment you are the full legal owner.
For comparison: an off-plan property under construction has no full Title Deed - it is recorded through an Oqood registration, and the Title Deed is issued only after the building is handed over. On the resale market there is no such wait - the certificate of ownership is issued on the day of the deal. You can always check the current procedures and fees on the official portal of the the Dubai Land Department (DLD).
How much a resale purchase costs: fees and transaction expenses
The price of the property itself is only part of the budget. To avoid surprises at the trustee's office, let's bring all the mandatory costs of a ready-property deal into a single picture. Importantly, there is no purchase tax and no annual property tax in Dubai - the main costs are one-off fees at re-registration. The figures are indicative and may change; check the current rates with the DLD.
| Cost item | Amount (indicative) | Who it's paid to |
|---|---|---|
| The DLD re-registration fee | 4% of the property value | The Land Department |
| DLD admin charge (ready home) | ~580 AED | The Land Department |
| Trustee-office services | ~4 000-4 200 AED | Registration Trustee centre |
| The developer's NOC | ~500-5 000 AED | The master developer |
| Agency commission | usually ~2% of the value + 5% VAT | Broker |
| Mortgage fees (if any) | the mortgage registration fee at the DLD + bank charges | The DLD and the bank |
In total, the 'add-on' to the price of a ready home usually comes to roughly 5.5-6% on the DLD side of the costs, plus the agent's commission. This is important to plan for in advance: the budget for a resale purchase is the price of the property plus about 7-8% in related costs. Next, we cover how to finance the purchase if you do not have the full sum in hand.
"When a client asks what to buy - a resale unit or an off-plan property - I always bring them back to a single question: do you need income now, or upside three years from now? A ready home is more : you see the actual walls, the actual view from the window, an actual tenant, and you hold the Title Deed in hand on the day of the deal. But resale has its own pitfalls, and almost all of them lie in the property's history. The first things I check are service-charge arrears and any mortgage held over the property by the seller: without a clean NOC, the deal simply stalls at the trustee. The second is the budget: resale is paid in full or through a mortgage, and a bank lends a non-resident roughly half the value, so the rest has to be in hand. Once these two points are settled in advance, buying a ready property in Dubai goes smoothly within a few weeks and starts working for you straight away."
Where a foreigner can buy resale: Dubai's freehold zones
A foreign national can buy property in Dubai in full freehold ownership only in specially designated areas. This applies to both the primary and resale markets - the rule is the same. Outside these zones, a foreigner can access only a long-term lease (leasehold) or other limited forms, but not full ownership with a Title Deed.
The most liquid freehold districts of Dubai for buying ready housing:
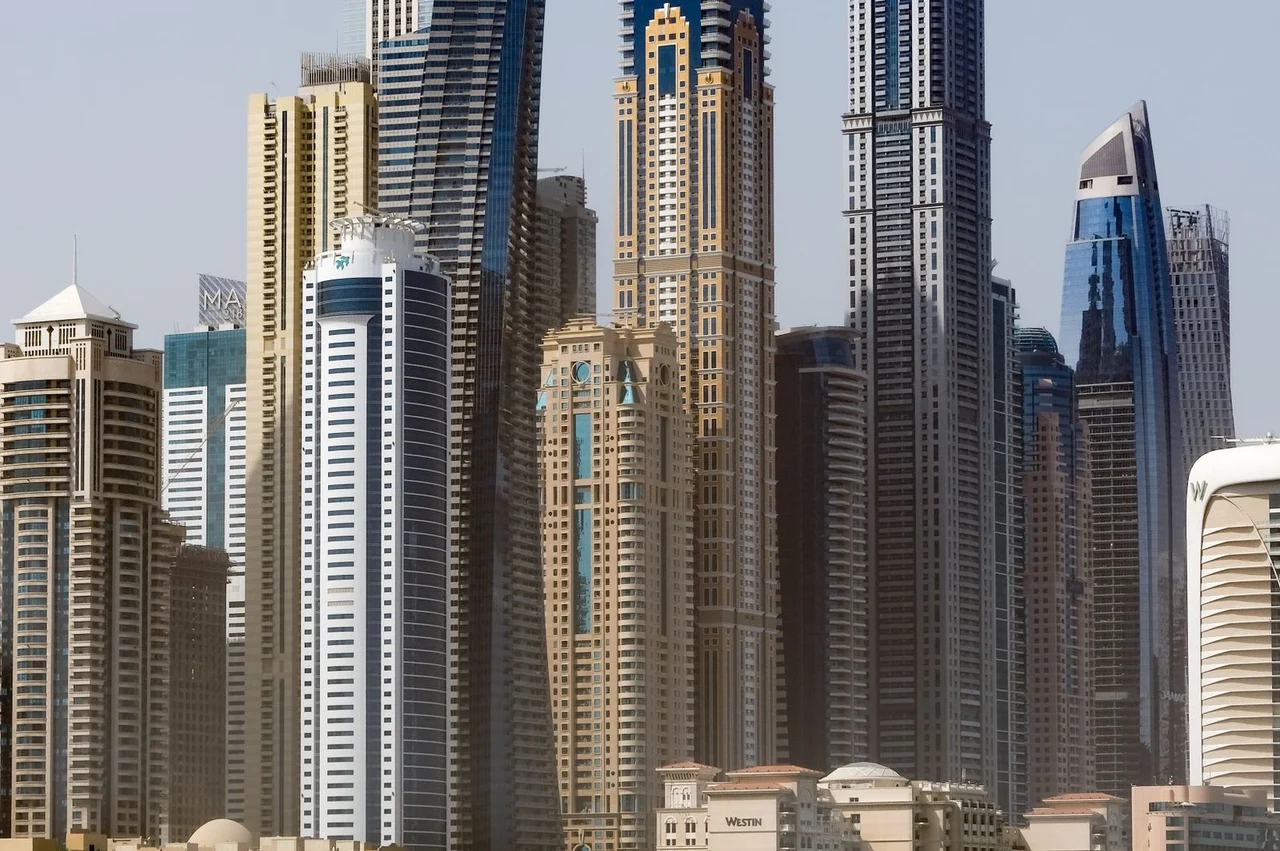
- Dubai Marina - high-rise apartments by the water, strong rental demand, well-developed infrastructure.
- Downtown Dubai - the premium centre by the Burj Khalifa, high prices and prestige.
- Palm Jumeirah - villas and apartments on the 'Palm,' the top segment.
- Business Bay - a business district by the canal, a balance of price and yield.
- JVC (Jumeirah Village Circle) - an affordable segment with a good rental yield.
- Dubai Hills Estate - a family district with villas and greenery.
When choosing a district for a resale property, look not only at the price but also at actual rental occupancy, the state of the community, and the size of the service charges - they directly affect your net yield. A ready home is convenient because all of these can be checked in reality, not against a project's promises. We track price trends by district in our review of Dubai property prices 2026.
Prices on Dubai's resale market 2026: the gap with new builds
Understanding the pricing picture is the foundation of a sensible purchase. In 2026, the Dubai market split clearly into two segments with different dynamics, and the gap between ready and under-construction housing became especially pronounced. Here are indicative figures based on market data from early 2026.
- The average price of resale. Ready housing traded at roughly around 1,690 AED per square foot - growth of around 5-6% over the year.
- The average price of new builds. Off-plan cost roughly around 2,030 AED per square foot and rose faster - by about 12% over the year.
- The off-plan premium. The gap between under-construction and ready housing per meter widened to roughly 29-31% in favor of new builds - meaning off-plan, per meter, is noticeably more expensive than resale.
- Market share. Off-plan accounted for about 72% of all residential deals in the first quarter of 2026, with resale making up around 28% - but it was precisely ready homes with tenants that showed resilient demand.
- Room to negotiate. In certain segments, resale sold roughly 5-15% below the peak values of the start of the year - private sellers are willing to negotiate.
The takeaway for the buyer: resale means a cheaper entry per meter and income straight away, while off-plan means a higher price per meter but with an installment plan and appreciation potential during construction. Which segment is more advantageous for you depends on your investment horizon and your need for immediate rental income.
Does buying resale grant a UAE residence visa
Buying a ready property in Dubai is not only an asset but also a potential basis for a residence visa. The principle here is the same for resale and off-plan: what matters is the value of the property, not whether it is ready or under construction. It is important to understand that this concerns a residence permit (a residence visa), not citizenship - a UAE passport is not granted for investment.
- A 2-year residence visa. Buying a property valued from roughly 750,000 AED grants the right to a 2-year residence visa with an Emirates ID.
- A 10-year Golden Visa. A property valued from 2,000,000 AED opens the path to a 10-year Golden Visa - renewable and self-sponsored. The holder sponsors their own family: a spouse, children with no age limit, and parents.
- A ready home is fit for use immediately. For the visa thresholds, the value on the Title Deed is what matters. A ready home with a completed certificate of ownership is convenient because the visa is arranged without waiting for the building's handover.
An important caveat for Russian buyers: visa-free entry for 90 days grants the right to stay in the country as a tourist, but living and working requires a residence visa with an Emirates ID, and property is one of the most reliable ways to obtain it. UAE citizenship, however, cannot be bought through investment - keep this in mind so as not to build false expectations.
Legal due diligence on the property: what to check before the deal
The main risk on the resale market is not the property itself but its 'history': debts, encumbrances, disputed documents. A ready home may look perfect yet carry invisible problems that surface at the trustee's office or even after the Title Deed is issued. That is why legal due diligence before signing Form F is not a formality but protection for your money.
What is always checked before buying a resale property:
- Authenticity of the Title Deed. The seller's certificate of ownership is checked against the DLD database - the property, the area, and the owner's name must match.
- Encumbrances and the seller's mortgage. If the property carries a mortgage, it must be paid off within the deal - this affects the payment structure and the timeline.
- Service-charge arrears. Without cleared debts, the developer will not issue the NOC. This is checked in advance so the deal does not stall at the finish.
- Being within a freehold zone. The property must be located in a zone where a foreigner can obtain full ownership.
- The accuracy of Form F. The contract must correctly set out the price, the deposit, the payment schedule, and the completion terms - errors here are expensive.
An experienced specialist carries out these checks before you pay the deposit, not after. It is at this stage that most of the resale market's risks are closed off. Buying a ready home in Dubai is safe exactly to the extent that the due diligence before the deal is done thoroughly.
We'll help you find and safely buy a ready home in Dubai
A resale purchase involves dozens of details on which it is easy to lose money: hidden service-charge arrears, a mortgage held by the seller, an inflated price, a problematic NOC, errors in Form F. A single unchecked detail can wreck the deal at the final step at the trustee's office or turn into costs even after the Title Deed is issued.
We handle the purchase of ready property in Dubai end to end: we verify the property's clean legal status and any debts, negotiate the price, support the signing of Form F, the issue of the NOC, and re-registration at the DLD, and, where needed, help with the mortgage and the residence visa. Discuss your objective with a BRIDGES GLOBAL expert - we'll find a property to fit your budget and goal and handle the deal without risk.
A mortgage on resale in Dubai: rates, LTV, and non-residents
A ready home is the most convenient option for a mortgage. The bank sees a real property, can carry out a valuation, and can set the collateral value, so ready properties are financed more readily than off-plan. Let's go over the terms of a mortgage on a resale property in Dubai in 2026 - the figures are indicative, and the specifics depend on the bank and the borrower's profile.
- LTV (share of financing). For a non-resident, the maximum LTV on a ready home is roughly 50-60% of the value, meaning a down payment of around 40-50%. A UAE resident can access more - up to 75-80%.
- The down payment. A non-resident, as a rule, needs to contribute 40-50% of the value from their own funds, plus the transaction costs.
- Rates. A market guide: variable rates of around 5.5-7%, and rates fixed for 1-5 years of about 4-5.5%. The exact rate depends on the bank, the amount, and the term.
- The loan term. Up to 25 years, but the older the borrower, the shorter the available repayment term.
- Processing timelines. A clean mortgage deal, from pre-approval to registration at the DLD, takes roughly 3-6 weeks.
A separate nuance is compliance. UAE banks carry out enhanced verification of the source of funds (KYC/AML), and not every bank extends financing to borrowers from certain countries. Everything is strictly within the law, with no sanctions-evasion schemes whatsoever. It is therefore best to start preparing documents on the origin of your funds in advance, before entering the deal.
Bottom line: who resale suits and who off-plan suits
Let's sum up, without tilting to one side. Secondary property in Dubai and new builds solve different problems, and the 'right' choice depends on your goal, not on the fashion of the market.
A ready home suits you if:
- you need rental income from day one, not in a few years' time;
- it matters to see and touch the actual property before buying;
- you have the full sum or you plan to take a mortgage;
- you want to quickly arrange a residence visa against an already-ready asset;
- you value predictability and are not prepared to risk construction delays.
Off-plan is a better fit for you if:
- a low entry threshold and a convenient installment plan from the developer matter more;
- you are willing to wait for handover for the sake of potential price growth during construction;
- you do not need immediate rental income.
There is no universal answer: resale offers certainty and income now, while off-plan offers an installment plan and upside on the horizon. A sensible strategy often combines both segments in a portfolio. If you want to work through your specific case - goal, budget, district, payment structure, and visa - we will help you choose the format and handle the deal end to end. Compare the two approaches in our articles on Dubai new builds and overall buying property in Dubai.
Frequently asked
Questions people ask before deciding
01What is secondary property in Dubai, in plain terms?
It is a ready property that has already been built, handed over, and issued a Title Deed - the certificate of ownership. It already has an owner who is selling the apartment or villa. Unlike an off-plan property still under construction, such a home can be inspected in person, moved into, or rented out immediately after re-registration at the Dubai Land Department.
02How does ready property differ from off-plan in Dubai?
A ready home is built, has a Title Deed, and can be occupied and rented out immediately, but it must be paid for in full or through a mortgage. An off-plan property takes 2-4 years to build, is registered via Oqood, and is sold with an installment plan from the developer, but generates no income until handover. Resale is roughly 25-30% cheaper per square meter; off-plan is more expensive per meter but comes with an installment plan.
03How much does it cost to buy a resale property in Dubai, all fees included?
Beyond the price of the property, budget for roughly 7-8% in related costs: the 4% DLD fee, an administrative charge of about 580 AED, trustee-office services of about 4,000-4,200 AED, the developer's NOC at 500-5,000 AED, and the agent's commission, usually around 2% plus 5% VAT. There is no purchase tax and no annual property tax in Dubai - the main costs are one-off charges at re-registration.
04What is the developer's NOC and why is it needed?
The NOC (No Objection Certificate) is a certificate from the master developer stating that the seller has no service-charge arrears and does not object to the deal. Without the NOC, the Land Department will not register the transfer of title. On the resale market the NOC is always mandatory; on the primary market (a direct purchase from the developer) it is not needed. It costs roughly 500-5,000 AED.
05How does the re-registration of the Title Deed on resale work?
The buyer and seller meet at the office of an accredited DLD trustee; the buyer pays the balance of the price, the 4% DLD fee, and the administrative charges. The Land Department cancels the old Title Deed and issues a new one in the buyer's name. From that moment you are the full legal owner. For a ready home, the Title Deed already exists - unlike an off-plan property, where it is issued after handover.
06Can you take out a mortgage on ready property in Dubai?
Yes, and it is the most convenient option for a mortgage: the bank sees a real property and can value it. A non-resident can obtain financing of roughly 50-60% of the value (a down payment of 40-50%), and a resident up to 75-80%. Rates are roughly 5.5-7% variable, or from 4-5.5% fixed for several years, with a term of up to 25 years.
07Resale or off-plan - which is more advantageous in 2026?
It depends on the goal. Resale is cheaper per meter, gives income from day one and certainty, but requires payment in full or a mortgage. Off-plan is more expensive per meter (a premium of roughly 29-31%) but comes with an installment plan and appreciation potential during construction. An investor after immediate rent leans toward a ready home; one after an installment plan and growth leans toward off-plan.
08Can you negotiate when buying resale in Dubai?
Yes, on the resale market prices are negotiable, unlike the primary market, where the developer holds a fixed price list. In 2026, in certain segments, properties sold roughly 5-15% below the peak values seen at the start of the year. A private seller has an interest in closing the deal and is often willing to give ground, especially if they are not tied to a hard deadline.
09Where can a foreigner buy resale in Dubai?
Only in freehold zones (designated areas), where a foreigner can obtain full ownership with a Title Deed: Dubai Marina, Downtown, Palm Jumeirah, Business Bay, JVC, Dubai Hills, and others. Outside these zones, only a long-term lease is possible. The rule is the same for resale and off-plan.
10How long does a resale deal take?
A clean deal with no encumbrances on the seller's side takes roughly 3-6 weeks: from signing Form F and paying the 10% deposit to the issue of a new Title Deed at the DLD. A mortgage adds time for bank approval, and a mortgage on the seller's side that has to be paid off lengthens the process. The fastest deals are clean, all-cash ones.
11Does buying resale grant a UAE residence visa?
Yes, just like an off-plan property - what matters is the value of the property, not its status. A property from 750,000 AED grants a 2-year residence visa, and from 2,000,000 AED a 10-year Golden Visa with the right to sponsor family. A ready home is convenient because the visa is arranged straight away, with no wait for handover. This concerns a residence permit, not citizenship - a UAE passport is not granted for investment.
12What are the risks of buying resale, and how do you avoid them?
The main risks are hidden service-charge arrears, a mortgage held by the seller, a problematic NOC, and errors in Form F. All of them are closed off by legal due diligence before the deposit is paid: the Title Deed is checked against the DLD database, encumbrances and debts are verified, and the contract is reviewed for accuracy. An experienced specialist runs due diligence in advance, not after the deal. A ready home, once bought, can be rented out immediately after re-registration - the income starts from day one.
Transparency
How this material was prepared
- Author
- Maria Stavru, real Estate Analyst, BRIDGES
- Terms and costs last verified
- June 2026
- Sources
- official government authorities of the relevant country and state publications
- Methodology
- government minimum requirements are stated separately from due diligence charges, state fees, legal and banking costs
Sources and methodology
Figures, terms and timelines are checked against official sources as of June 2026. Link availability verified in August 2026. Third-party blogs and agent websites are not used as a source of programme terms.
- [1]Federal Authority for Identity, Citizenship, Customs and Port Security (ICP)Visas, residence statuses, Emirates IDicp.gov.ae/en
- [2]Official portal of the UAE GovernmentGolden visa and residence visasu.ae/en/information-and-services/visa-and-emirates-id/residence-visas/golden-visa
Methodology: tables and charts state government minimum investment requirements; due diligence charges, state fees, legal, banking and other costs are calculated separately and are not included in the minimum thresholds.
About the author
Related materials
What to read next
 ArticleUAE citizenship by investment in 2026: is there a program and what really works?
 ComparisonDubai or Abu Dhabi in 2026: where to live, work and buy property
 AnalysisWhat is due diligence and why the Caribbean is rejecting applications
Personal programme selection is conducted by Anna Kovalevskaya, Head of Legal, BRIDGES.
Buying property in UAE: what to check
Title, encumbrances, outstanding debts and what to look for in the contract.
