Residency · Turkey
Medical insurance for a Turkey residence permit in 2026: private, SGK, and DASK
Updated: ·9 min read·Expert reviewed
Terms and costs verified: undefined
Contents
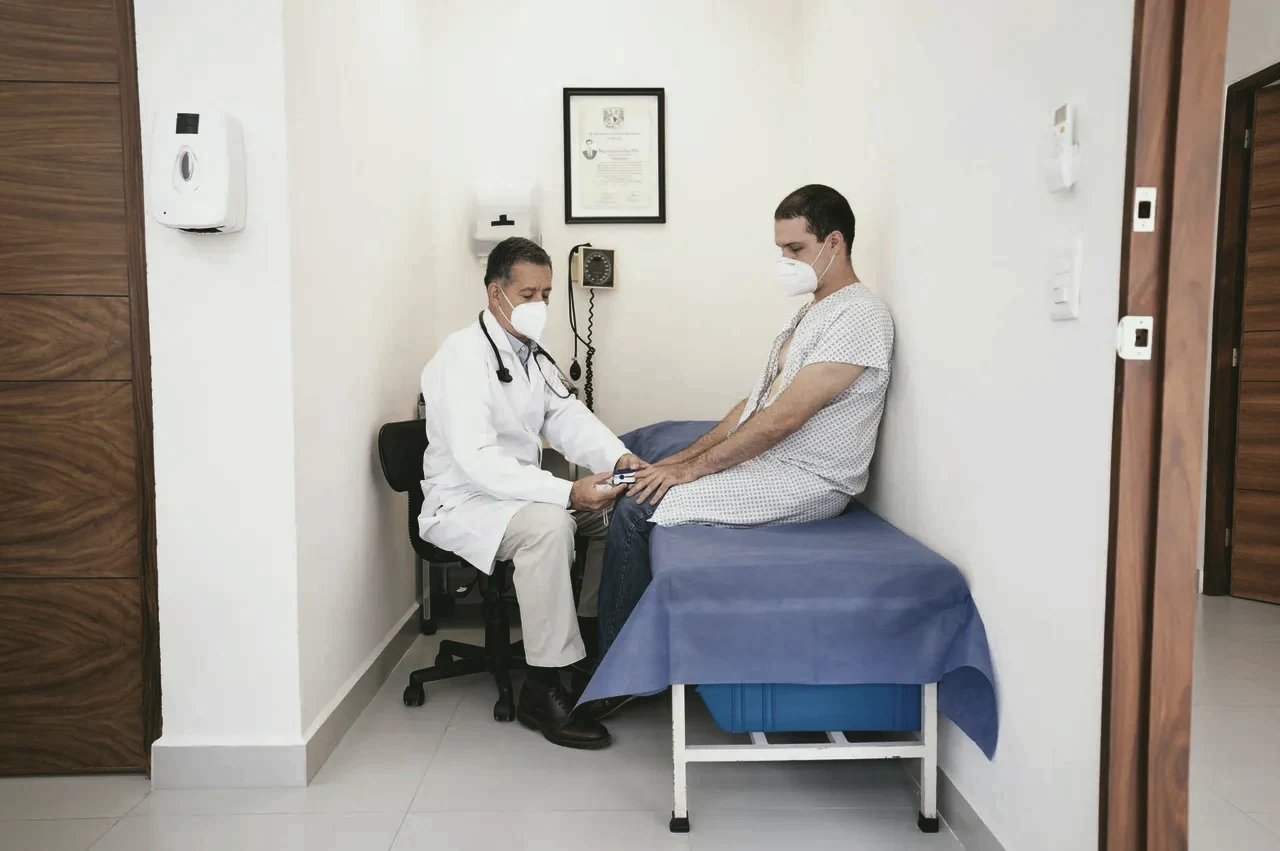
Without valid medical insurance, an application for a Turkish residence permit simply won't be accepted - this is a legal requirement, not a formality. We break down how private insurance differs from state SGK, what coverage the migration service wants to see, how much the policy costs by age, why people over 65 are often exempt, and why a property owner needs separate earthquake insurance, DASK. With 2026 figures and typical mistakes that lead to refusal.
Why no residence permit is granted at all without insurance
Medical insurance for a Turkish residence permit isn't a nice add-on but a strict condition for document acceptance. It's set out in Article 15 of Law No. 6458 "On Foreigners and International Protection": any foreigner filing for a residence permit (ikamet izni) is required to have valid medical insurance covering the entire requested permit term. No insurance - the application simply won't be accepted, and if the error surfaces at the review stage, the migration service (göç idaresi) will issue a refusal.
The state's logic is simple: it doesn't want a foreigner who falls ill to burden public healthcare or be left without help. That's why insurance is required at the initial filing, at every renewal, and regardless of the grounds - whether a property, tourist, family, or work residence permit. The policy is attached to the document package and uploaded to the e-ikamet system with the other papers. We break down in detail what goes into the package in our article ondocuments for a Turkey residence permit- insurance is one of the mandatory items there alongside TAPU and the address certificate.
Two insurance types: private and state SGK
In Turkey there are two fundamentally different coverage systems for a foreigner, and they shouldn't be confused.
- Private insurance (özel sağlık sigortası, also yabancı sağlık sigortası)- a policy from a Turkish insurance company that the foreigner buys themselves. This is the main and, for most, the only available option, especially in the first year.
- State insurance (genel sağlık sigortası, GSS / SGK)- an equivalent of mandatory health insurance, giving access to state hospitals almost for free. But it isn't open to a foreigner right away: a residence track record is needed.
The difference isn't only in money. A private policy is arranged within an hour online and accepted by the migration service from day one, but mostly covers contracted clinics with limits. SGK is cheaper long-term and gives broad access to state healthcare, but you still need to "grow into" it. Most of those who are just relocating - throughA Turkey residence permitthrough property or other grounds - start with private insurance and switch to SGK later once eligible.
Private insurance: what the policy must contain
The migration service doesn't accept just any document with the word "insurance", but a policy with a strictly defined minimum coverage. Tourist insurance for short trips (up to 90 days) doesn't work - it'll be turned away for the residence permit. Specifically a foreigner residence-permit policy is needed, issued by a Turkish company and valid for the entire permit term.
The minimum set of coverage göç idaresi wants to see in the policy is split into two parts:
- Inpatient treatment (yatarak tedavi)- hospitalization, surgery, intensive care, ward and meal costs, serious procedures like chemo and radiotherapy, dialysis, disposable medical supplies. At contracted clinics this is usually covered with no limit, at non-contracted ones - with an annual limit (around 50,000 TL) and the insured's own share.
- Outpatient treatment (ayakta tedavi)- doctor visits, medication, tests, X-rays - within the annual limit, most often in the range of 5,000-10,000 TL.
The policy is usually arranged for 1 or 2 years, matching the requested residence permit term. It's important that the coverage start date matches the permit period, not "backdated" or with a gap - such mismatches also become grounds for refusal.
How much private insurance costs by age
The residence-permit policy price depends primarily on age: the older the person, the higher the risk for the insurer and the more expensive the premium. Gender, health condition, the chosen clinic network, and coverage limits also matter. According to Turkish insurers' 2026 data, an annual residence-permit policy falls in the range of approximately 1,500 to 8,000 TL, and for basic options the lower bar starts even lower.
| Age | Policy type | Approximate price per year |
|---|---|---|
| 18-35 years | Basic for the residence permit | from ~1,500 TL |
| 35-50 years | Standard | ~2 000-4 000 TL |
| 50-65 years | Standard/extended | ~4 000-8 000 TL |
| 65+ years | The policy isn't mandatory (see below) | - |
The figures are approximate: the insurer calculates the final premium individually, based on the health questionnaire, the chosen network of contracted clinics, and the plan's content. Extended coverage with larger limits and a broad hospital network will cost more than the basic one, which covers only the göç idaresi-mandatory minimum. A policy with the minimum set is enough for filing for the residence permit - there's no point overpaying for a premium plan just for the permit.
Exemption for those aged 65 and older
One of the most useful nuances: private insurance for the residence permit is mandatory for foreigners aged 0 to 65. Those who turned 65 are generally exempt from the requirement to buy a private policy - precisely because at this age insurers either refuse or charge unaffordable premiums, and the state chose not to make insurance an insurmountable barrier for the elderly.
This matters especially for those relocating to Turkey in retirement. The scenario is broken down in detail in our guide ona Turkey residence permit for retirees: a person 65+ usually just needs to confirm they can pay for treatment themselves, with no policy purchase. But there are nuances. First, some regional migration offices may request alternative proof of solvency or a notarized statement - practice isn't always uniform across the country. Second, the exemption applies to the applicant personally: if a spouse under 65 files on the same grounds, they still need a policy. So age 65+ is worth discussing in advance with the local office, not treating as an automatic guarantee.
State SGK: to whom and when it opens up
Genel sağlık sigortası (GSS) through the SGK institute is access to Turkish state healthcare on almost the same terms as for citizens. But it isn't available to a foreigner right away. The basic condition: you need to live continuously in Turkey under a valid residence permit for at least one full year. This means that for the entire first year in the country - whether you're a new homeowner, retiree, or relocator - the only working option for the residence permit is private insurance.
Besides the year of residence, there are other requirements for voluntary SGK enrollment:
- the applicant must not be insured under another country's social insurance system;
- must not be covered by other medical insurance in Turkey;
- the application is filed in person at the local SGK office, documents - in Turkish or with an official translation.
A valid residence permit will be needed, a certificate from the social insurance or consulate of the home country that the person isn't insured there, and a signed commitment statement. Students are a separate case: they can join GSS within three months of enrollment, without waiting a year. The voluntary SGK contribution for foreigners is noticeably more modest than the cost of a good private policy, so many consciously switch to it after the first year.
Private or SGK: what to choose
There's no real choice in the first year - SGK is unavailable, period. But once a year has passed, a fork appears, and the decision depends on how the person lives in Turkey and uses healthcare.
- Private insurance- fast, flexible, gives access to private clinics with no queues and often service in Russian or English. The downside - the price rising with age and limits on outpatient care.
- SGK- cheaper long-term, opens state hospitals and a broad list of procedures, but this is state healthcare with queues and predominantly Turkish, and processing requires a visit to the office and gathering certificates.
In practice, many combine both: keeping SGK as the base and adding private insurance for access to specific private hospitals. For the residence permit itself, one thing is essential - that at the time of filing or renewal you have valid coverage recognized by the migration service. Which of the two - is a matter of convenience and budget, not admission to the permit. If you're only at the start of the path and figuring outthe Turkey residence permit process, budget for a private policy specifically in the first year.
"Clients underestimate insurance the most - and unfairly: it's exactly what causes most of the document returns we see, not complicated things. A typical story: a person bought six-month tourist insurance because it's cheaper, and then is surprised why göç idaresi won't accept the package. The policy must specifically be for ikamet izni, with inpatient and outpatient coverage, and cover the entire residence permit term - with no gaps in dates. I separately tell those over 65: the private-policy exemption exists, but don't treat it as automatic - regional offices sometimes ask to confirm solvency, and it's better to find this out in advance. And if the residence permit goes through property - don't forget DASK, without it even connecting water and electricity will stall. I always advise checking the policy before filing, not after a refusal: redoing it costs weeks, checking it costs half an hour."
DASK: earthquake home insurance
If the residence permit is processed through property, a second mandatory insurance often forgotten appears - DASK (Doğal Afet Sigortaları Kurumu), mandatory state earthquake home insurance. Turkey is a seismically active country, and the law requires DASK for all residential properties registered in the land cadastre and located within municipal boundaries. This applies to foreign owners exactly the same as to citizens - Turkish citizenship isn't needed.
DASK covers only the building's structure - walls, floor slabs, foundation - against damage from an earthquake and related phenomena (landslide, tsunami, a seismic-caused explosion). It doesn't insure furniture, appliances, and finishing, for which a separate voluntary home insurance is needed. A practical point: without a valid DASK policy, electricity, water, and gas can't be connected to the property, and the sale-purchase deal can't be completed. Since a property residence permit is built exactly around the purchased property (see our breakdowncitizenship and investment in Turkey), DASK effectively becomes part of the owner's mandatory set. The policy is inexpensive and quick to arrange, but its absence can stall both processing and renewal.
How and where to get insurance
A private policy for the residence permit is the simplest to arrange: it's issued by almost all major Turkish insurers, the application can be filed online or through an agent, and the policy arrives the same day. A foreign passport, a Turkish foreigner ID number, and a basic health questionnaire will be needed. It's important to tell the insurer directly that the policy is needed "for ikamet izni" - then you'll be issued the version with the minimum coverage recognized by göç idaresi, not regular tourist insurance.
The usual sequence of actions is:
- obtain or have a Turkish foreigner ID number (also needed for the whole document package);
- choose an insurer and plan for the needed residence permit term - 1 or 2 years;
- arrange the policy so the coverage start date matches the permit period;
- upload the policy to the e-ikamet system with the other documents.
DASK for housing is arranged through insurance companies or banks by the property's address and cadastral data. SGK, once eligible, - only in person at the local social insurance office with certificates gathered in advance. If there are multiple grounds and family members, it's more convenient to gather the insurance requirements for each into one list in advance so nothing falls through at the filing stage.
Insurance for the family: spouse and children
When not one person but a family files for a residence permit, insurance is needed for each applicant separately - the migration service treats a general "family" policy as a set of individual coverages, and it's important each one has their own valid policy for the entire permit term. This applies to the spouse and children who process the family residence permit as dependent members.
An age nuance comes up here again. If, say, the main applicant is over 65 and exempt from a private policy, this exemption doesn't automatically extend to a younger spouse or children - they'll still need insurance. Policies for children are generally inexpensive, for a spouse - at their age's rate. Family members also don't reach SGK simultaneously: the year of continuous residence is counted for each, and whoever entered later gets the right to state insurance later. So for a family filing it's simpler to keep everyone on private policies synchronously, with matching dates, and decide the SGK switch later for each separately. A mismatch in coverage terms between family members is a common reason one of them's application "hangs".
Common mistakes that lead to refusal
Most insurance problems aren't about money but about carelessness. Here are the mistakes that most often cost a refusal or returned documents:
- Bought tourist insurance.A policy for short trips (up to 90 days) isn't accepted for the residence permit - specifically a foreigner policy for ikamet izni is needed.
- Insufficient coverage.If the policy lacks the mandatory minimum for inpatient and outpatient treatment, göç idaresi won't accept it.
- The policy term is shorter than the residence permit term.Coverage must cover the entire requested permit period, not part of it.
- A gap or shift in dates.The policy start date doesn't match the residence permit period - the document will be returned.
- Forgot DASK for a property residence permit.Without it both utilities and processing get stuck.
- Relied on the 65+ exemption without checking.The regional office may request alternative confirmation - better to find out in advance.
One thing unites all these mistakes: they surface at the review stage, when redoing the package is costly in time. It's cheaper to check the policy before filing than to get refused and file again.
What Turkish healthcare covers with this insurance
What real access to treatment each insurance gives is a question worth deciding before relocating, not after the first doctor visit.
| Insurance type | What it's for | What it covers / cost |
|---|---|---|
| Private (özel sağlık sigortası) | Mandatory for filing a residence permit (0-65 years) | Inpatient and outpatient care at contracted clinics; ~1,500-8,000 TL a year by age |
| State (SGK / GSS) | Access to state healthcare after 1 year of residence | A broad list of procedures at state hospitals; the voluntary contribution is noticeably lower than a private policy |
| DASK | Mandatory for a residential property residence permit | Only the building's structure against earthquakes; an inexpensive annual policy |
| Voluntary home insurance | Optional, supplements DASK | Furniture, appliances, finishing, flooding, theft - not mandatory for the residence permit |
The main budget takeaway: for the first year, budget a private residence-permit policy for each family member (except those 65+), and DASK immediately when buying housing. This is exactly the mandatory insurance minimum without which the documents won't go through. If you want to work out the full estimate for your case and family in advance, it makes sense todiscuss the situation with our lawyers- they'll gather the insurance, timing, and grounds requirements into one clear plan.
How to check the policy definitely fits
Before filing, the policy is worth checking against three points, and this can be done yourself. First - make sure it's specifically a foreigner policy for ikamet izni, not tourist insurance; the document itself usually has a note on compliance with migration service requirements. Second - check the coverage: both inpatient (yatarak) and outpatient (ayakta) treatment must be present with limits no lower than the minimum. Third - check the dates: coverage start no later than the filing date, end - no earlier than the residence permit term.
Official requirements for the residence permit and document composition are published by Turkey's migration directorate aten.goc.gov.tr, and the conditions and procedure for joining state healthcare - the social insurance institute atsgk.gov.tr. The rules are periodically clarified and may differ by region, so always check the current edition and the specific office's practice before filing. If you want to fully remove the risk of a refusal due to insurance - let us check your policy and package before filing: this is cheaper than redoing the application after it's returned.
Frequently asked
Questions people ask before deciding
01Is medical insurance mandatory for a Turkey residence permit in 2026?
Yes. Under Article 15 of Law No. 6458, any foreigner filing for a residence permit is required to have valid medical insurance for the entire permit term. Without it the application won't be accepted, and a review will produce a refusal. This applies to both the initial filing and every renewal.
02How does private insurance differ from state SGK?
Private (özel sağlık sigortası) - a policy from a Turkish company that the foreigner buys themselves; available from day one and accepted by the migration service. SGK (genel sağlık sigortası) - state insurance with access to state healthcare, but it opens to a foreigner only after a year of continuous residence.
03How much does private insurance cost for the residence permit?
According to 2026 data - approximately from 1,500 to 8,000 TL a year, basic options can be cheaper. The price depends on age, gender, health condition, clinic network, and coverage limits. A policy with the minimum coverage recognized by göç idaresi is enough for filing.
04Is it true that people over 65 don't need insurance?
A private policy is mandatory for ages 0 to 65, while those who turned 65 are generally exempt. But this isn't always automatic: some regional offices request alternative proof of solvency. Age 65+ is worth discussing in advance with the local migration office.
05Will regular tourist insurance work?
No. Tourist insurance for short trips (up to 90 days) isn't accepted for the residence permit. Specifically a foreigner policy for ikamet izni is needed, issued by a Turkish company, with inpatient and outpatient treatment coverage for the entire permit term.
06What minimum coverage must the policy have?
The policy must include inpatient treatment (yatarak tedavi) - hospitalization, surgery, intensive care - and outpatient (ayakta tedavi) - doctor visits, medication, tests, X-rays - with limits no lower than the set minimum. Without these two blocks, the migration service won't accept the policy.
07When can a foreigner switch to state SGK?
After continuous residence in Turkey under a valid residence permit for at least one full year. It's additionally required not to be insured under another country's social insurance or another Turkish policy. The application is filed in person at the local SGK office. Students can join GSS within three months of enrollment.
08What's more advantageous - private insurance or SGK?
In the first year there's no choice: SGK is unavailable, private is needed. After a year, SGK is cheaper long-term and gives access to state healthcare, but this means queues and Turkish. Private is faster and more convenient, with private clinics. Many combine both: SGK as the base plus a private policy for needed hospitals.
09Why is DASK needed for a property residence permit?
DASK is mandatory state earthquake home insurance for all residential properties within municipal boundaries, including foreign-owned property. Without valid DASK you can't connect water, electricity, and gas or complete the deal. Since a property residence permit is built around the property, DASK is part of the owner's mandatory set.
10Does each family member need separate insurance?
Yes. For a family filing, each applicant needs a policy for the entire permit term. The 65+ exemption doesn't automatically transfer to a younger spouse or children. Family members don't get on SGK simultaneously - the year of residence is counted separately for each.
11How fast can you get a policy for the residence permit?
A private policy is issued by almost all major Turkish insurers online or through an agent, usually the same day. A foreign passport, a Turkish foreigner ID number, and a health questionnaire are needed. Say directly that the policy is needed for ikamet izni, to get the version with the recognized minimum coverage, and upload it to e-ikamet.
12What most often leads to refusal because of insurance?
A tourist policy instead of a residence permit policy, insufficient coverage, a term shorter than the permit term, a gap or shift in dates, forgotten DASK for a property residence permit, and relying on the 65+ exemption with no check with the regional office. All of this surfaces at review, so the policy is better checked before filing.
Transparency
How this material was prepared
- Author
- Viktoria Lebedeva, managing Director, Private Clients, BRIDGES
- Terms and costs last verified
- Sources
- official government authorities of the relevant country and state publications
- Methodology
- government minimum requirements are stated separately from due diligence charges, state fees, legal and banking costs
Sources and methodology
Figures, terms and timelines are checked against official sources. Link availability verified in August 2026. Third-party blogs and agent websites are not used as a source of programme terms.
- [1]Presidency of Migration ManagementResidence permits and citizenshipen.goc.gov.tr
- [2]General Directorate of Land Registry and CadastreProperty transactions and valuationwww.tkgm.gov.tr/en
Methodology: tables and charts state government minimum investment requirements; due diligence charges, state fees, legal, banking and other costs are calculated separately and are not included in the minimum thresholds.
About the author
Related materials
What to read next
 ArticleTurkish bank account for Russians in 2026: how to open and what nuances to consider
 ComparisonCaribbean or Turkey: Citizenship for Contribution or Real Estate in 2026
 AnalysisWhat is due diligence and why the Caribbean is rejecting applications
Personal programme selection is conducted by Anna Kovalevskaya, Head of Legal, BRIDGES.
Residency in Turkey: timelines and requirements
Grounds, document list, presence requirements and what is needed for renewal.
